Category: Blog

Your blog category

  • Mule Account Scam India: Your Bank Account Used for Fraud

    Mule Account Scam India: Your Bank Account Used for Fraud

    A stranger offers you ₹5,000. All you have to do is let them use your bank account for a few transactions. No hacking. No effort. Just easy money.

    Weeks later, your bank account is frozen. Police call you in for questioning. A cybercrime case is filed. And suddenly, you are not a victim. You are an accused.

    This is not a hypothetical situation. This is happening to thousands of Indians right now.

    It is called a mule account scam. And according to the India Fraud Report 2026, it is the number one fraud threat facing Indian businesses and individuals today.

    What Is a Mule Account?

    A mule account is a bank account that is used to receive and transfer money obtained through fraud. The account holder may or may not know that their account is being used for criminal activity.

    Scammers need these accounts because they cannot use their own. If stolen money goes directly into a scammer’s personal account, police can trace it immediately. So they route it through someone else’s account first. Sometimes through five or ten accounts in a chain. By the time the money reaches its final destination, the trail is so complex that tracking it becomes extremely difficult.

    The person whose account is used is called a “money mule.” In many cases, this person is an ordinary citizen who was either tricked into lending their account or knowingly rented it out for a small commission.

    Either way, the law treats you as part of the crime.

    How Big Is This Problem in India?

    The numbers are staggering.

    The India Fraud Report 2026, released on March 27, 2026, found that 48 percent of Indian enterprises now identify mule networks as the most difficult fraud threat to detect and control. This ranks higher than phishing, identity theft, account takeovers, and social engineering.

    Banking sector fraud losses have reached ₹36,014 crore according to the RBI Annual Report 2024-25.

    In just the last few weeks, multiple major mule account cases have been busted across the country.

    In Karimnagar, Telangana, police uncovered a mule account network that routed ₹137 crore through just 8 bank accounts. Thirteen people were arrested, including two bank employees who helped open the accounts. The accused had been luring innocent people by offering a 2 percent commission on deposits.

    In Mangaluru, police busted a USDT pipeline scam where over 70 mule bank accounts were used to route cybercrime money from India to China. The total amount involved was ₹85 crore. The stolen money was converted to Tether (USDT), a cryptocurrency, and transferred abroad. Only ₹13.43 crore could be frozen.

    In just three months — December 2025 to February 2026 — Karnataka police alone picked up 68 people running mule account networks. Behind those arrests? A staggering 869 bank accounts tied to nearly 8,800 cybercrime cases. And that is just one state. The reality is, this is not some scattered, small-time fraud. It is a full-blown industry, running like clockwork across every corner of India.

    How Do Scammers Recruit Mule Account Holders?

    Scammers have refined their recruitment methods to target specific groups of people. Understanding how they approach victims is the first step toward protecting yourself.

    1. The “Easy Money” Job Offer

    This is the most common method. You receive a message on WhatsApp, Telegram, or even a direct phone call. Someone offers you a simple deal: let them deposit money into your account and transfer it forward. You keep a commission, usually 1 to 5 percent per transaction.

    It sounds harmless. But every rupee passing through your account is stolen money from a fraud victim somewhere in India.

    2. The Fake Part-Time Job

    Some scammers disguise mule recruitment as a legitimate job. They post advertisements for “payment processing executives” or “finance assistants” on job portals. The job description involves receiving payments into your personal account and forwarding them to other accounts. No office. No interview. Just your bank details.

    By the time you realize the job is fake, your account has already processed lakhs of rupees in fraudulent transactions.

    3. Direct Purchase of Bank Accounts

    An investigation published in March 2026 revealed that a nationwide network is openly buying bank accounts from individuals for prices ranging from ₹5,000 to ₹3.5 lakh. The racket spans states like Madhya Pradesh, Bihar, and West Bengal.

    Agents approach people directly, especially in rural and semi-urban areas. They collect personal details, Aadhaar cards, PAN cards, and bank passbooks. In some cases, they even open new accounts in the victim’s name without fully disclosing the purpose.

    These accounts are then used to route money from phishing scams, investment frauds, digital arrest schemes, and other cybercrimes. Once the money enters, it is quickly withdrawn or moved through multiple layers, making recovery nearly impossible.

    4. Targeting Students and Unemployed Youth

    Students looking for pocket money and unemployed youth are prime targets. Scammers approach them on college campuses, through social media, or via local contacts. The pitch is always the same: “Just let some money come into your account. No risk. Easy cash.”

    Many of these young people do not understand that they are participating in money laundering. By the time police come knocking, the scammer is gone. The student is left holding the legal responsibility.

    What Happens When Your Account Is Used as a Mule?

    The consequences are severe and often come without warning.

    1. Your Bank Account Gets Frozen

    This is usually the first sign. When a fraud victim reports a cybercrime and police trace the money trail, every account in the chain gets flagged. Your account is frozen, meaning you cannot withdraw, transfer, or access your own money.

    Under Section 106 of the Bharatiya Nagarik Suraksha Sanhita (BNSS), 2023, police can seize or freeze any bank account suspected of being connected to a crime. The freeze can happen even if you are not directly accused. If the stolen money simply passed through your account, it can be locked.

    2. Police Investigation and Questioning

    Once your account is flagged, you will likely receive a call or notice from the cyber crime cell. You will be asked to explain every transaction, where the money came from, why you received it, and where it went.

    If your answers do not match the records, or if the investigating officer finds evidence that you knowingly participated, you could be arrested.

    3. Criminal Charges

    Depending on the case, mule account holders can be charged under multiple laws.

    Under the Bharatiya Nyaya Sanhita (BNS), 2023, Section 318 deals with cheating and dishonestly inducing delivery of property. If your account was used to move fraud money, this section applies.

    Section 111 of the BNS covers organized crime, which now explicitly includes cybercrimes and economic offences. If police can show that you were part of a network, even as a small link, you could face charges under this section. The penalties include life imprisonment for serious cases.

    Under the Information Technology Act, 2000, Sections 66C and 66D deal with identity theft and online cheating. These sections are commonly invoked in cybercrime investigations involving mule accounts.

    If the money was routed internationally or converted to cryptocurrency, the Prevention of Money Laundering Act (PMLA) may also apply.

    4. The Impact on Innocent People

    Here is the harsh reality. Your account can be frozen even if you had no idea it was being used for fraud. A 2025 judgment from the Delhi High Court noted that bank accounts of individuals who are neither accused nor suspects can still be frozen during cybercrime investigations.

    The court called blanket freezing of such accounts “arbitrary, disproportionate, and violative of Articles 19(1)(g) and 21 of the Constitution.” But despite such rulings, freezes continue to happen because the process moves faster than the legal safeguards.

    Merchants who accepted a payment from a fraud victim’s compromised account have had their accounts frozen. Freelancers who received a payment from a client whose account was later linked to a fraud chain have been caught up in investigations. Small business owners have lost access to their working capital for months.

    The investigation may eventually clear you. But the financial and emotional damage during that period can be devastating.

    How to Know If Someone Is Trying to Make You a Mule

    Scammers use specific language and patterns to recruit mule account holders. If you hear any of the following, treat it as a warning.

    “Just use your bank account for some transactions. You will get commission.”

    “We need your account to process client payments. This is a part-time job.”

    “Let me deposit some money in your account. Just transfer it where I tell you.”

    “Give me your bank details, Aadhaar, and PAN. I will open an account for business.”

    “No skills needed. No experience required. Just receive and send money.”

    “You will earn ₹500 to ₹5,000 per transaction. Easy work from home.”

    Any offer that asks you to receive money into your personal account and transfer it elsewhere without a clear, documented business reason is a mule recruitment attempt. No exceptions.

    What to Do If Your Bank Account Has Been Frozen

    If your account has already been frozen due to a cybercrime investigation, do not panic. There are legal steps you can take.

    Step 1: Find Out Why the Account Was Frozen

    Contact your bank immediately. Ask for the written reason for the freeze, the name of the authority that issued the order, and the FIR number or complaint number linked to the case. Under the law, you have the right to be informed of the reason for the freeze and the authority behind it.

    Step 2: Contact the Investigating Officer

    Reach out to the cyber crime cell handling the case. Provide all documents that prove your transactions were legitimate. This includes business invoices, employment records, contracts, or any other proof that the money entering your account was from a lawful source.

    Step 3: Submit a Representation to the Magistrate

    Under Section 106(3) of the BNSS, police are required to report any account seizure to the jurisdictional Magistrate immediately. If they have not done so, the freeze itself is legally vulnerable.

    You can file an application under Section 503 of the BNSS (return of property) before the Magistrate. The Magistrate has the authority to examine whether the freeze was lawful and order de-freezing if it was not.

    Step 4: File a Writ Petition if Needed

    If the freeze continues despite your representation, you can file a writ petition before the High Court under Article 226 of the Constitution. Multiple High Courts have recently ordered de-freezing of accounts where the freeze was done without proper procedure.

    The Delhi High Court in February 2026 held that police authorities have no power under Section 106 of the BNSS to debit-freeze or attach bank accounts. Such action can only be ordered under Section 107 by a competent Magistrate.

    Step 5: Consult a Cyber Crime Lawyer

    If the amount involved is significant or if you are facing criminal charges, consult a lawyer who specializes in cybercrime and financial fraud cases. Early legal intervention can prevent the situation from escalating.

    Check: How to Recover Money Lost in Online Scam in India (Step-by-Step Guide 2026)

    How to Protect Yourself from Becoming a Money Mule

    Prevention is far easier than dealing with the aftermath. Follow these rules.

    • Never share your bank account, UPI ID, or internet banking credentials with anyone. No legitimate job or business requires access to your personal bank account for processing payments.
    • Never agree to receive and forward money for anyone. Even if the person is a friend, relative, or someone you met online. If the money is stolen, you are legally responsible.
    • Do not open bank accounts on behalf of others. If someone asks you to open an account using your documents for “business purposes,” refuse. You will be the legal owner, and all liability falls on you.
    • Verify any job offer that involves handling money. If a job posting asks you to process payments through your personal account, it is a scam. Legitimate companies use corporate accounts and registered payment gateways.
    • Be cautious of unusually high commissions for simple tasks. If someone offers you 2 to 5 percent just for letting money flow through your account, ask yourself why they cannot use their own account. The answer is that they cannot, because the money is illegal.
    • Monitor your bank account regularly. If you notice unfamiliar transactions, contact your bank immediately and report it to 1930, the National Cyber Crime Helpline.
    • Talk to your family members. Elderly parents, college-going children, and financially vulnerable relatives are common targets. Make sure they understand that lending their bank account to anyone is dangerous and potentially criminal.

    What to Do If You Suspect You Are Being Recruited as a Mule

    If someone has come to you with an offer like the ones we talked about in this article, act fast. Do not share your personal or banking details with them. Stop talking to them completely. Save every message, call recording, and document they sent you. Then report it on cybercrime.gov.in or just call 1930.

    If you already gave them your bank details but no money has moved yet, call your bank right away and change your passwords and PIN immediately.

    If money has already come into your account and gone out without you knowing, go to both your bank and the cyber crime cell. The faster you report it, the better your chances of being seen as a victim and not as someone who was part of it.

    How to Report a Cyber Crime in India: Complete Step-by-Step Guide (2026)

    Check Suspicious Links and UPI IDs on ScamDekho

    If someone sends you a suspicious link, a UPI ID for payment, or asks you to scan a QR code as part of a “job” or “commission” offer, verify it before you act.

    ScamDekho offers free tools to help you check before you click:

    • URL Checker: Paste any link and instantly check if it is safe or flagged as malicious.
    • UPI ID Checker: Verify whether a UPI ID is linked to known fraud reports.
    • QR Code Scanner: Scan any QR code to check the destination before making a payment.

    Visit scamdekho.in and use these tools. It takes 10 seconds and could save you from losing your money or your freedom.

    Frequently Asked Questions

    What is a mule account in simple words?

    A mule account is a normal bank account that is used by fraudsters to receive and move stolen money. The account holder is called a money mule. They may be recruited through fake job offers, direct cash payments, or social engineering.

    Can I go to jail for being a money mule?

    Yes. Even if you did not commit the original fraud, allowing your bank account to be used for transferring stolen money is a criminal offence. You can face charges under the BNS, IT Act, and in serious cases, the PMLA. Penalties range from fines to imprisonment.

    My bank account was frozen but I did not do anything wrong. What should I do?

    Contact your bank for the written reason, reach out to the investigating officer with proof of legitimate transactions, and file an application before the jurisdictional Magistrate under Section 503 BNSS for de-freezing. Consult a cyber crime lawyer if the freeze continues.

    How do I report a mule account recruitment attempt?

    Call 1930 (National Cyber Crime Helpline) or file a complaint on cybercrime.gov.in. Save all evidence including messages, phone numbers, and any documents shared by the recruiter.

    Can my account be frozen even if I am not accused of any crime?

    Yes. During cybercrime investigations, police can freeze any bank account that received or transferred suspected fraud money, even if the account holder is not directly accused. However, courts have ruled that such blanket freezes without proper procedure are illegal and can be challenged.

    How are mule accounts detected by police?

    Police trace the money trail from the victim’s complaint using UPI transaction logs, bank records, KYC details, IP addresses, and device fingerprinting. Every account in the chain gets flagged, regardless of the account holder’s involvement.

    If you found this article helpful, share it with your friends and family. The more people understand how mule accounts work, the harder it becomes for scammers to find their next victim.

    Have you received a suspicious job offer or a request to use your bank account? Check it on ScamDekho before you respond.
  • Telegram Task Scam India: Fake Work From Home Jobs And How to Recover Money

    Telegram Task Scam India: Fake Work From Home Jobs And How to Recover Money

    You get a message out of nowhere. “Hi, I have a part-time job opportunity for you. Simple tasks, no joining fee. You can earn ₹500 to ₹5,000 per day from home.”

    It sounds harmless. Even exciting.

    But thousands of Indians who responded to exactly this kind of message have lost anywhere between ₹10,000 and ₹51 lakh. Not because they were careless. Because the scam is designed to look completely real.

    This is the Telegram task scam. And it is currently one of the most active cyber frauds in India.

    What Is the Telegram Task Scam?

    The Telegram task scam is a type of online job fraud where scammers contact you through WhatsApp, Telegram, or SMS with a fake work-from-home offer. The job involves simple tasks like liking YouTube videos, rating hotel listings, subscribing to channels, or adding products to a shopping cart.

    The scam works in two phases. First, they pay you small amounts to build your trust. Then, they trap you into making large payments by promising bigger returns — which never come.

    By the time most victims realize what has happened, they have already transferred lakhs into the scammer’s account.

    How the Scam Works: Step by Step

    Understanding the exact pattern is the best way to protect yourself.

    Step 1: The First Message

    You receive a message on WhatsApp, Telegram, or SMS from an unknown number. The message offers a simple part-time job — rating products, completing surveys, or liking videos. There is no joining fee mentioned. The tone is friendly and professional.

    Step 2: You Are Added to a Telegram Group

    Once you show interest, you are added to a Telegram group. The group has multiple members who regularly post screenshots of their earnings. These are fake accounts playing the role of “happy workers” to make the group look legitimate.

    Step 3: The First Task — Small and Paid

    You are assigned a simple task. Like a YouTube video, subscribe to a channel, or rate a product. Once done, you receive a small payment — ₹150 to ₹500 — directly in your bank account or UPI. This is the trust-building phase.

    Step 4: Bigger Tasks, Bigger “Profits”

    After a few paid tasks, you are told about “prepaid tasks.” These involve depositing a small amount — say ₹2,000 — to unlock a task that returns ₹3,500. The first round works. You get your money back plus profit. This is intentional. They are making you comfortable.

    Step 5: The Trap

    Now you are told about a high-value task that requires a deposit of ₹25,000, ₹50,000, or more. The fake dashboard on their app shows your balance growing. But when you try to withdraw, the system shows an error. You are told to pay more to “unfreeze” your account. This cycle continues until you stop paying or run out of money.

    Step 6: They Disappear

    Once they have taken enough money, the Telegram group is deleted. The website goes offline. All contact numbers stop responding.

    Real Cases From India

    1. Rohtak, Haryana — Jatin was 20-something, looking for extra income, when a Telegram message offered him a simple work-from-home job — rating hotels online. It sounded harmless. He joined a group, completed a few small tasks, and deposited ₹7,000. His dashboard showed ₹14,000 in returns almost immediately.

      That moment of excitement cost him everything.

      Encouraged by what looked like real profit, he kept investing. By the time he stopped, he had lost ₹10.14 lakh. A case was eventually registered at the cyber police station under the Bharatiya Nyaya Sanhita — but the money was gone.

      2. Palanpur, Gujarat — A 28-year-old pharma executive received a Telegram message promising ₹5,000 to ₹20,000 per day working from home. He downloaded what he thought was a legitimate wallet app and started transferring money. Over the next two months, he made 18 separate transfers. Total loss: ₹9.21 lakh. The only amount he ever managed to withdraw was ₹1,300 — before the fraudsters blocked him and disappeared.

      3. Hyderabad — An engineer lost ₹51 lakh to a Telegram group that claimed to be an e-commerce company called “P&B Solutions.” The job involved listing products online. The dashboard showed growing profits. Every time he tried to withdraw, they asked for one more deposit to unlock his earnings. The profits were fabricated. The company was fake. The money was gone.

      And these are just three stories.

      According to the Pune Cyber Cell, residents of Pune alone lost ₹27.23 crore to task-based fraud since 2023. Pune is one city. Imagine the national number.

      Warning Signs You Must Know

      The scam follows a predictable pattern. These are the signs that tell you something is wrong:

      • Unsolicited job offer from an unknown number. No genuine employer contacts you randomly on WhatsApp or Telegram without you applying first.
      • No interview, no verification, no joining process. Real jobs have a hiring process. If someone just adds you to a group and hands you work, that is a red flag.
      • Small initial payments to build trust. Scammers always pay you first. This is not generosity. It is bait.
      • A fake app or website with a “balance” you cannot withdraw. If your earnings are showing on a private app that you were asked to download, and withdrawals keep failing, you are being trapped.
      • Pressure to deposit more to “unlock” funds. No legitimate employer will ask you to invest your own money to receive your salary.
      • Fake testimonials in the Telegram group. Multiple members posting earnings screenshots are usually bots or scammer accounts.

      Who Do These Scammers Target?

      Scammers do not pick victims randomly. They go after specific people — and they are very good at finding them.

      Their primary targets are people who genuinely need extra income. Students looking for pocket money between classes. Homemakers who want to earn something from home without a traditional 9 to 5 job. People who were recently laid off and are under financial pressure. Freshers who have been applying for months and still cannot find a full-time position.

      These are people with a real need. And scammers know exactly how to speak to that need.

      The promise of earning ₹500 to ₹5,000 per day — no skills required, no experience needed, work from your phone — is not a random pitch. It is carefully designed to appeal to people who feel like options are limited and time is running out.

      That is what makes it so effective. And that is what makes it so cruel.

      How to Recover Money Lost in a Telegram Task Scam

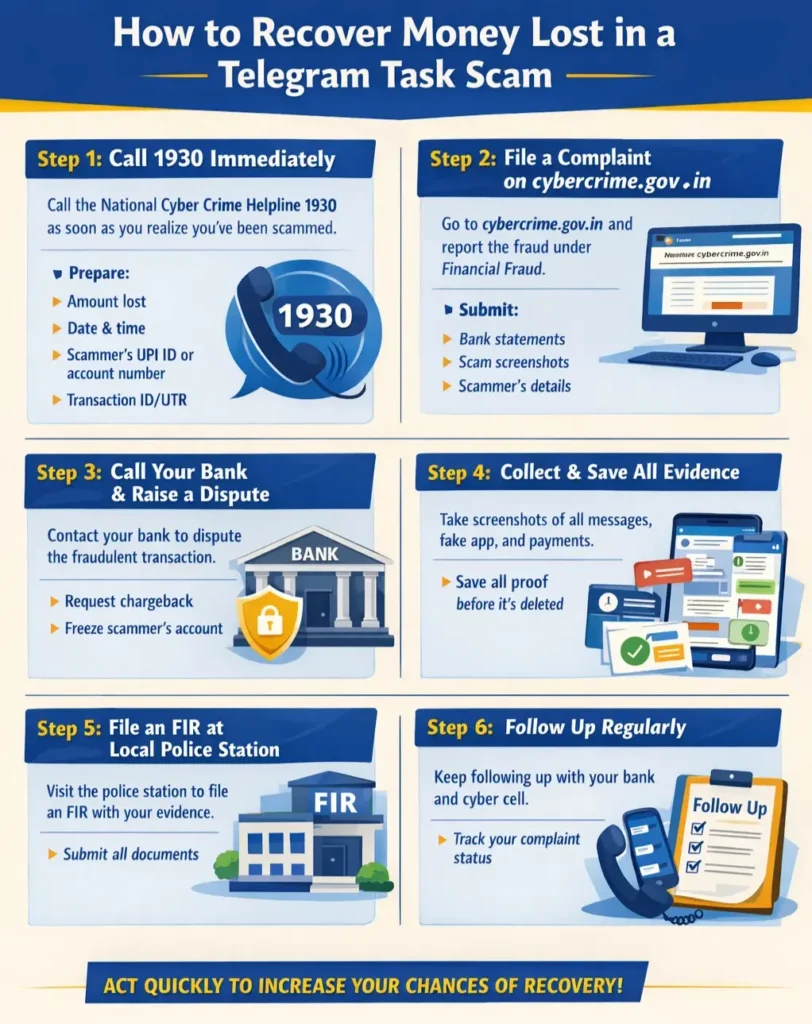
      How to recover money lost in Telegram task scam - 6 steps infographic

      If you have already lost money, do not assume it is gone forever. Recovery is possible — but only if you act fast. The first few hours are the most critical window.

      Here is exactly what you need to do, in order.

      Step 1: Call 1930 Immediately

      The moment you realize you have been scammed, call 1930. This is the National Cyber Crime Helpline run by the Indian Cyber Crime Coordination Centre (I4C).

      Keep these details ready before you call:

      • The exact amount transferred
      • Date and time of the transaction
      • The UPI ID or bank account number you sent money to
      • Transaction reference number or UTR number

      When you report quickly, authorities can alert the receiving bank to freeze the scammer’s account before the money is moved further. Even a 30-minute delay can reduce your chances significantly.

      Step 2: File a Complaint on cybercrime.gov.in

      Go to the National Cyber Crime Reporting Portal and file an online complaint under Financial Fraud.

      You will need to submit:

      • Transaction ID and bank statement
      • Screenshots of all Telegram messages and the fake job offer
      • The scammer’s phone number, UPI ID, or Telegram username
      • Details of the fake app or website if you downloaded one

      This complaint creates an official record and is forwarded to the cyber cell for investigation.

      Step 3: Call Your Bank and Raise a Dispute

      Contact your bank’s customer care immediately after filing the complaint. Ask them to:

      • Raise a chargeback or dispute on the fraudulent transaction
      • Flag or freeze the beneficiary account
      • Block your account temporarily if you suspect further unauthorized access

      The sooner your bank is informed, the higher the chance they can coordinate with the receiving bank to hold the funds.

      Step 4: Collect and Save All Evidence

      Before the scammers delete the Telegram group — which they do very quickly — take screenshots of everything:

      • All messages and task instructions
      • The fake earnings dashboard or app screenshots
      • Payment confirmations and bank transaction records
      • The scammer’s profile details and phone number

      Once the group is deleted, this evidence becomes very hard to recover.

      Step 5: File an FIR at Your Local Police Station

      If the amount lost is significant, visit your nearest police station and file an FIR. Carry printed copies of all your evidence. An FIR is important because it formally initiates a legal investigation and strengthens your case for fund recovery.

      Step 6: Follow Up Regularly

      Filing a complaint is not enough. Follow up with your bank and the cyber cell using your complaint reference number. Many victims lose money simply because they do not follow up after the initial report.

      For a detailed guide on the full recovery process, read: How to Recover Money Lost in an Online Scam

      Can You Actually Get the Money Back?

      Recovery depends on how quickly you report and where the money went.

      Recovery is more likely when you reported within 1 to 2 hours of the fraud, the money was transferred within India via UPI or bank transfer, and the scammer’s account still has funds.

      Recovery becomes difficult when you waited several hours or days before reporting, the money was moved through multiple accounts quickly, or the funds were converted to cryptocurrency.

      This is why calling 1930 within minutes — not hours — is the single most important thing you can do.

      How to Verify if a Job Offer Is Real

      Before responding to any online job offer, take these steps.

      Search the company name on Google and check whether it has an official website, registered address, and verifiable contact details. Look it up on the Ministry of Corporate Affairs website at mca.gov.in to check if it is a registered company.

      Ask for a formal offer letter with the company’s letterhead and GST number. No legitimate company will refuse this.

      Do not download any app that was not sent from the official Google Play Store or Apple App Store. Fake wallet apps are always shared as APK files or through third-party links.

      Never pay any amount to receive a salary. This is the clearest sign of fraud.

      How ScamDekho Can Help

      If you receive a suspicious Telegram message with a link, UPI ID, or a website URL, check it on ScamDekho before clicking or paying.

      Go to ScamDekho.in, enter the link or UPI ID, and get an instant scam risk report. The tool analyzes the input using real fraud signals so you can make an informed decision before it is too late.

      Final Thoughts

      The reason this scam works is not because people are careless. It is because scammers are patient.

      They spend days, sometimes weeks, making you feel like you have finally found something real. Small payments come through. The dashboard looks promising. Everything feels like it is working — until the moment it does not.

      By then, the money is already gone.

      There is one rule that can protect you from all of this. No real employer will ever ask you to deposit money to receive your own earnings. No legitimate job requires you to pay to unlock a task, activate an account, or release a withdrawal. The moment someone asks you for a deposit to access your own money — stop. That is the scam revealing itself.

      It does not matter how long you have been talking to them. It does not matter how much the dashboard is showing. It does not matter how convincing they sound. Walk away.

      If you or someone you know has already been targeted, do not wait. Call 1930 or file a complaint at cybercrime.gov.in as soon as possible. Quick reporting gives you the best chance of recovering something.

      Stay alert. And if an opportunity ever feels too easy — it probably is.

    1. SIM Swap Scam India: What It Is, Warning Signs and How to Stay Safe

      SIM Swap Scam India: What It Is, Warning Signs and How to Stay Safe

      Your phone shows “No Service.”

      You think — network problem. You restart your phone. Still nothing. You put it aside and plan to call the network provider later.

      But here is what you do not know yet.

      While you are waiting for your signal to come back, someone else is already using your phone number. They are receiving your bank OTPs. They are resetting your net banking password. They are transferring money out of your account — one transaction at a time.

      By the time you figure out what is happening, your account is empty.

      This is the SIM swap scam. And it is one of the most dangerous frauds in India today — because your phone does not even ring. You feel nothing until the money is already gone.

      What Happened to Real People

      Before anything else, read these real cases. These are not made-up stories.

      1. A Mumbai businessman lost ₹7.5 crore

      A Mumbai-based company owner lost ₹7.5 crore in a SIM swap fraud. Scammers got access to his company bank account by swapping his SIM card and made multiple unauthorised transactions within minutes. He called the 1930 cyber helpline immediately after realising what happened. Police managed to freeze ₹4.65 crore within four hours — but the rest was already withdrawn and gone.

      2. A Tirupur businessman lost ₹19.99 lakh

      A businessman from Tirupur lost ₹19.99 lakh after fraudsters obtained a duplicate SIM card without proper verification and accessed his bank account. He had no idea his SIM had been swapped until he checked his bank balance the next morning.

      3. A Delhi lawyer lost lakhs — without sharing a single OTP

      A Delhi lawyer lost lakhs from his account in a SIM swap scam. He never responded to any calls from the scammers and never shared his OTP or personal information — yet the fraudsters still managed to gather his details and carry out the fraud.

      This last case is the most frightening one. Because it shows you do not even have to make a mistake for this scam to happen to you.

      Check: AI Voice Cloning Scam in India

      So What Exactly Is SIM Swap Fraud?

      Let us explain this simply.

      Your phone number is connected to your bank account. Every time your bank needs to confirm it is really you — when you log in, transfer money, or reset your password — it sends an OTP to your phone number.

      In a SIM swap scam, fraudsters trick your mobile network provider into transferring your phone number to a SIM card that they control. Once that happens, they receive all your calls, messages, and most importantly — your OTPs. With that, they can access your bank accounts, reset your passwords, and transfer your money without you knowing.

      Think of your SIM card as the key to your bank. A SIM swap scam is someone making a copy of that key — and you do not find out until they have already used it.

      How Do Scammers Actually Do This?

      It happens in stages. Here is the full picture in simple words.

      First — they collect your personal details

        The scam starts with the fraudster gathering your personal information. They get this through fake emails, fake websites, social media, or data leaks from apps you have used. They need your name, address, date of birth, and identity document details — enough to pretend to be you.

        You may not even know your data was stolen. It could have happened months ago through a data breach you never heard about.

        Then — they go to your telecom provider

        Armed with your details, the scammer contacts your mobile network — Jio, Airtel, or Vi. They pretend to be you. They say your SIM is lost or damaged and they need a new one. The service provider verifies them using the details they have collected, deactivates your old SIM, and gives the scammer a new active SIM with your number.

        In some cases, they do not even go to a store. They call customer care. In rare cases, they bribe a telecom employee to skip the verification steps.

        Then — your phone goes silent

        Your phone loses signal. No calls. No messages. No internet. Most people assume it is a network issue and wait.

        That waiting time is exactly what the scammer needs.

        Then — your money disappears

        Once they control your number, the scammer requests password resets on your bank accounts. They receive your OTPs on their phone. They log into your net banking and UPI apps, reset your passwords, and transfer your money — all within minutes.

        By the time your signal comes back or you contact your network provider, the transactions are already done.

        The eSIM Version — Happening More

        There is a newer, sneakier version of this scam that does not even require a fake visit to a telecom store.

        A scammer calls you pretending to be from Jio or Airtel customer care. They say your network quality will improve if you switch to an eSIM. They sound completely professional and helpful.

        They ask you to share a verification code that was sent to your current number — just to confirm the switch.

        The moment you share that code, your number gets transferred to their device. Your physical SIM becomes useless. And the entire fraud plays out exactly as described above.

        The rule is simple: No telecom company ever calls you to upgrade your SIM. If someone calls asking you to switch to an eSIM — hang up.

        6 Warning Signs Your SIM May Have Been Swapped

        Your phone will show signs. You just need to know what to look for.

        Your phone suddenly shows No Service for no reason No location change. No bad weather. No network outage in your area. If your phone loses signal out of nowhere — call your telecom provider from someone else’s phone immediately. Do not wait.

        Not sure if a message or link from your telecom provider is real? Check it on ScamDekho before clicking anything.

        OTPs stop arriving on your phone You are trying to log into your banking app and the OTP is not coming. This is a serious sign. Someone else may already be receiving it.

        You get a password reset notification you did not request Your bank or email sends a notification that your password was changed — but you did not do it. Act immediately.

        Unknown transactions appear in your bank account Even small ones. Scammers sometimes test with a small amount before transferring the big amount.

        You receive a call from someone claiming to be from your telecom company Telecom companies do not call you asking you to update or change your SIM card. If you receive such a call — especially from a regular 10-digit number — it is a scam. End the call immediately.

        Your telecom app shows a new SIM registered that you did not do Most telecom apps let you check your account activity. Log in once a month and verify no new SIM or device has been registered under your number.

        Also Read: How Fake NGOs and Charity Frauds Are Stealing From Kind-Hearted Indians

        How to Protect Yourself — Simple Steps That Actually Work

        You do not need to be a tech expert to protect yourself. These steps are easy and take less than 10 minutes.

        Call your telecom provider and add extra verification for SIM changes

        Call Jio on 198, Airtel on 121, or Vi on 199. Ask them to add an extra security step — like a PIN or a personal question — for any SIM replacement or porting request on your number. This means even if a scammer has your personal details, they cannot swap your SIM without that extra step.

        Turn on email alerts for all bank transactions

        Most banks let you set up email notifications in addition to SMS. Even if your SIM gets swapped and SMS stops coming, email alerts will still reach you. Enable this today.

        Set a daily transaction limit on your UPI and net banking

        Log into your banking app and set a daily transfer limit. This limits how much damage can happen even if someone gets into your account.

        Do not share your Aadhaar or PAN on WhatsApp

        Scammers gather your KYC documents through various means — fake agents, phishing messages, and data leaks. Never share your Aadhaar, PAN, or bank details over WhatsApp, SMS, or email unless you are 100% certain of who you are sending it to.

        Use app-based authentication where possible

        Where your bank or app gives you the option to use an authenticator app instead of SMS OTP — use it. App-based OTPs cannot be intercepted through a SIM swap.

        Check your phone signal daily

        It sounds simple, but it works. If your phone loses signal unexpectedly — especially during banking hours — treat it as an emergency until proven otherwise.

        If You Think Your SIM Has Been Swapped — Do This Right Now

        Do not panic. Act fast — that is the only thing that matters.

        Step 1 — Call your telecom provider immediately from someone else’s phone. Jio: 198, Airtel: 121, Vi: 199. Tell them your SIM may have been swapped and ask them to block your number and cancel any duplicate SIM.

        Step 2 — Call your bank’s 24×7 helpline and ask them to freeze all transactions linked to your mobile number.

        Step 3 — Change your net banking password and UPI PIN from a different device — not your own phone.

        Step 4 — Call 1930, the National Cyber Crime Helpline, and report the fraud immediately.

        Step 5 — File a complaint at cybercrime.gov.in. Select “SIM Swap Fraud” as the category.

        Step 6 — Save every piece of evidence — screenshots of unknown transactions, call logs, and any suspicious messages you received.

        Acting fast genuinely helps. When the Mumbai businessman called the 1930 helpline immediately after the fraud, cyber police managed to freeze ₹4.65 crore out of ₹7.5 crore within just four hours. The faster you report, the better your chances of getting your money back.

        Why Your SIM Card Is So Valuable to a Scammer

        Most people think of their SIM as just something that makes calls work. But in 2025, your SIM card is actually the master key to your entire financial life.

        Every bank account, every UPI app, every financial service in India uses your mobile number for verification. TRAI has introduced a 7-day restriction on SIM porting after a new SIM is issued — meaning your number cannot be moved to another network for 7 days after a new SIM is given. This gives you a window to detect and report the fraud.

        But rules alone cannot protect you. Only awareness can.

        Conclusion

        The SIM swap scam does not need you to click a link. It does not need you to share an OTP. It does not even need you to answer a call. A Mumbai businessman lost ₹7.5 crore, a Tirupur businessman lost ₹19.99 lakh, and a Delhi lawyer lost lakhs — without making any obvious mistake.

        The only warning is your phone going silent.

        If that ever happens to you unexpectedly — do not assume it is a network problem. Call your telecom provider from another phone within minutes. That one call could be the difference between saving your money and losing everything.

        Stay safe — and share this with your family and friends who use mobile banking.

      1. How to Recover Money Lost in Online Scam in India (Step-by-Step Guide 2026)

        How to Recover Money Lost in Online Scam in India (Step-by-Step Guide 2026)

        The number of online scams in India has risen significantly in recent years. This has affected people of all ages. From fake UPI payment requests and QR code scams to job scams and phishing link scams, and even update messages for KYC details, scammers are always finding new ways to scam people and steal their hard-earned money. What makes these scams more serious is that they appear so real and genuine. It is only when the scammer has taken the money that the victim realizes they have been scammed.

        The biggest mistake that most people make after being scammed is that they don’t know what to do next. They either think that the money is gone for good and that there is nothing they can do. This is not true. In most cases, it is actually possible to recover the money. However, this can only be done if the right steps are taken. Timing is one of the most important aspects in this case. The first few hours after being scammed are the most important. This is because only in this time frame can the transaction be traced and stopped.

        In this guide, you will learn how to recover the money that has been scammed by scammers in India. This is not just general knowledge that you can find anywhere else. This is a step-by-step guide that will tell you how the system actually works.

        Immediate Steps to Take After Online Fraud

        Step 1: Immediately Call 1930 (Within Minutes)

        The moment you realize the fraud, call 1930, managed by the Indian Cyber Crime Coordination Centre.

        • Tell them: amount, time, transaction ID
        • They will alert the bank instantly
        • Helps in freezing the scammer’s account

        Pro Tip: Don’t wait even 10–15 minutes

        Step 2: Report on Cyber Crime Portal

        Go to the National Cyber Crime Reporting Portal

        • Select: Financial Fraud
        • Enter:
          • UPI ID / bank details
          • Screenshots
          • Transaction ID

        This creates official complaint proof

        Step 3: Inform Your Bank & Block Transaction

        Call your bank or visit branch immediately.

        Ask them to:

        • Freeze transaction
        • Block your account (if needed)
        • Raise chargeback request

        Faster bank action = higher recovery chance

        Step 4: Secure Your Accounts

        If scam involved OTP/link:

        • Change bank password
        • Reset UPI PIN
        • Remove unknown devices
        • Enable 2-factor authentication

        Prevents further money loss

        Step 5: Track Complaint Status

        • Note your complaint number
        • Follow up with bank + portal
        • Visit cyber cell if needed

        Many people skip this → delay hota hai

        Step 6: File FIR (If Required)

        If amount is high:

        Helps in legal recovery

        Visit nearest police station

        File FIR with all proof

        Can You Recover Money Lost in Online Scam?

        One of the most common queries people have is whether recovery is even possible. Well, the answer to this varies depending on a number of factors.

        When Recovery is Possible:

        • The reporting of the fraud was done within 1-2 hours
        • The money is still available in the scammer’s account
        • The transaction took place within India
        • The transaction type was UPI, bank transfer, or wallet

        When Recovery Becomes Difficult:

        • The reporting of the fraud was done after several hours or even days
        • The money transfer took place across several accounts
        • The transaction type involves cryptocurrency

        How the Recovery Process Works in India

        Understanding the process helps you stay informed and realistic.

        1. You report the fraud via helpline or portal
        2. The complaint is forwarded to cyber authorities
        3. Banks are notified about the fraudulent transaction
        4. The scammer’s account is identified
        5. Remaining funds are frozen or put on hold
        6. Investigation is conducted
        7. Refund is processed if funds are still available

        This process may take time depending on the complexity of the case, but early reporting ensures that action starts immediately.

        Also Read: KYC Scam in India: Fake Bank Messages That Are Stealing Your Money

        RBI Guidelines on Online Fraud

        The Reserve Bank of India has also issued guidelines to safeguard the interests of customers in the event of unauthorized transactions.

        According to RBI rules:

        1. If you report the fraud immediately, your liability can be zero
        2. Banks are liable to take action once the fraud is reported
        3. You are not liable for any system-related frauds

        However, if you delay in reporting the fraud, your liability increases and recovery also becomes difficult.recovery becomes harder. This is why immediate action is critical.

        Documents Required for Filing Complaint

        To ensure a smooth process, keep the following details ready:

        • Transaction ID or reference number
        • Bank statement
        • Payment screenshots
        • Chat or message proof
        • Scammer’s details (number, UPI ID, etc.)
        • ID proof (if required)

        Providing accurate and complete information helps authorities act faster.

        How to Check Online Scam Through ScamDekho

        1. Go to ScamDekho.in
        2. Choose which type of scam you want to check (Messages, Link, Screenshot, UPI Fraud)
        3. Click “Check Scam”
        4. See Results is this input safe or scam.

        Common Mistakes That Reduce Recovery Chances

        Many victims unknowingly reduce their chances of recovery due to simple mistakes:

        • Waiting too long before reporting the fraud
        • Not calling the helpline immediately
        • Assuming small amounts are not worth reporting
        • Deleting important evidence like chats or screenshots
        • Not informing the bank on time

        Avoiding these mistakes can significantly improve your chances of getting your money back.

        Types of Scams Where Recovery is Possible

        Recovery is more likely in certain types of scams, especially those involving domestic transactions:

        • UPI fraud
        • QR code scams
        • Fake job scams
        • KYC update scams
        • OTP-based fraud
        • WhatsApp or SMS scams

        In these cases, the money often remains within the banking system for some time, making it easier to trace and freeze.

        Real Case Example

        A victim in Delhi lost ₹25,000 through a fake UPI request. Instead of waiting, he immediately called the cyber helpline and reported the incident on the official portal. His bank was notified quickly, and the scammer’s account was frozen before the money could be withdrawn. Within a short period, the amount was successfully recovered.

        This example clearly shows that quick action can make a real difference.

        Final Thoughts

        It is natural to be stressed if you lose money in an online scam, but the best thing to do in this situation is to remain calm and act quickly. People think that once the money is lost, there is no way to retrieve it, but this is not the case. With proper action and quick recovery steps, it is quite possible to retrieve the money.

        The first thing to remember in this situation is that the first few hours are the most important. By calling the helpline, reporting the scam, and informing the bank, you are on the right track. At the same time, it is also important to remain alert and cautious in the future to avoid such situations.

        It is best to remain informed if you want to protect yourself from online scams.

      2. 10 Ways to Check Fake Job Offer in India Before You Get Scammed

        10 Ways to Check Fake Job Offer in India Before You Get Scammed

        Getting a job offer feels good. Especially when the salary is decent and the company sounds legitimate.

        But here is something worth thinking about — did you actually apply to this company? Did they reach out to you out of nowhere? Are they asking you to join within a few days?

        If yes, slow down.

        Fake job offers are one of the fastest growing scams in India right now. Scammers target freshers, people between jobs, and anyone actively looking for work. They send emails, WhatsApp messages, and even printed-looking offer letters that are hard to tell apart from the real thing.

        The trap is always the same. You get excited, you trust the process, and somewhere along the way you end up paying a registration fee, a training deposit, or sharing documents you should never have shared. By the time something feels wrong, the damage is already done.

        The scary part is not that these scams exist — it is how convincing they look.

        This guide covers 10 practical ways to verify any job offer you receive in India, the red flags that are easy to miss, and what to do if you think you have already been targeted.

        1. Verify the Company’s Online Presence

        Before anything else, check whether the company actually exists.

        Search the company name on Google. A real company will have a working website with an About Us page, contact details, and usually a careers section. It does not have to be fancy — but it should clearly tell you who they are, what they do, and how to reach them.

        Also look them up on LinkedIn. Most legitimate companies have an active page with real employees listed. If you cannot find the company anywhere, or the website looks rushed and half-finished, that is your first warning sign.

        Do not ignore it.

        2. Check the Email Address Carefully

        The email address tells you a lot — if you know what to look for.

        A genuine company will always contact you from an official domain. Something like hr@companyname.com. Not a Gmail. Not a Yahoo. Not a Hotmail.

        Also look closely at the spelling. Scammers often use addresses like hr@companynamee.com or hr@company-name-india.com — close enough to look real at a quick glance, but wrong on closer inspection.

        And if the email starts with “Dear Candidate” instead of your actual name, be careful. Real recruiters know who they are writing to.

        3. Never Pay Money for a Job

        This is the most important point in this entire guide. Read it carefully.

        No real company will ever ask you to pay money to get a job. Not for registration. Not for training. Not for a security deposit. Not for an ID card. Never.

        Scammers often make these fees sound reasonable — sometimes they even promise a refund after joining. But once you transfer the money, they disappear. The job was never real.

        If anyone asks you to pay via UPI, bank transfer, or any payment app as part of a hiring process — stop all communication immediately. There is nothing more to verify. It is a scam.

        4. Carefully Analyze the Offer Letter

        Fake offer letters can look surprisingly professional. But if you look closely, the cracks start to show.

        Check for the company’s official logo, correct address, and proper contact information. The formatting should be clean and consistent throughout the document. Watch for spelling mistakes, grammar errors, blurry logos, or missing signatures — these are all signs that the document was put together carelessly.

        If something about the letter feels slightly off, trust that feeling. You can also search for real offer letter samples from that company online and compare them side by side.

        5. Contact the Company Directly

        This is one of the simplest and most effective checks — and most people skip it.

        Go to the company’s official website, find their contact number or HR email, and reach out directly. Ask them whether the offer you received is genuine. It takes five minutes and can save you from a very expensive mistake.

        If the company has no idea who you are or says the offer is fake, you have your answer. If they confirm it is real, you can proceed with confidence.

        Do not use the contact details mentioned in the offer letter itself. Always find them independently.

        6. Watch Out for Unrealistic Job Offers

        If an offer sounds too good to be true, it usually is.

        High salary for minimal work. Immediate joining without any interview. No experience required for a senior role. These are classic signs of a fake offer designed to attract people who are desperate or in a hurry.

        Real companies invest time in hiring the right person. They do not skip interviews, they do not offer extraordinary packages to unknown candidates out of nowhere, and they do not pressure you to decide within 24 hours.

        Whenever an offer feels unusually generous or unusually easy — slow down and verify.

        7. Avoid WhatsApp and Telegram Job Offers

        If someone is offering you a job entirely over WhatsApp or Telegram, be very careful.

        Scammers love these platforms because they are informal, fast, and hard to trace. Messages come from unknown numbers, there is no official communication trail, and victims are often asked to make payments through the same chat.

        Legitimate companies use email for formal communication. They do not conduct hiring processes entirely through messaging apps. If a job offer arrives only on WhatsApp or Telegram with no proper email follow-up or official documentation, treat it as suspicious.

        8. Search for Reviews and Scam Reports

        A quick Google search can reveal a lot.

        Type the company name along with words like “scam,” “fake job offer,” or “fraud” and see what comes up. Check Quora and Reddit as well — these platforms often have threads where people share their experiences with fake recruiters and fraudulent companies.

        If multiple people have reported the same company for similar reasons, take that seriously. Other people’s bad experiences exist to warn you.

        9. Verify Job Listings on Portals

        Even established job portals like Naukri, LinkedIn, and Indeed occasionally have fake listings. Do not assume a listing is genuine just because it appears on a trusted platform.

        When you come across a job posting, check the recruiter’s profile carefully. See if the company has an officially verified page on the platform. Read the job description closely — if it is vague, asks for personal details upfront, or directs you to contact someone on WhatsApp, be cautious.

        Always apply through the company’s official career page when possible.

        10. Evaluate the Interview Process

        A real hiring process takes effort — from both sides.

        You should expect at least one proper interview where your skills, experience, and fit for the role are assessed. Real recruiters ask meaningful questions. They want to know if you are the right person for the job.

        If you are selected after a two-minute chat, or without any interview at all, something is wrong. Scammers skip the interview process because they are not actually hiring anyone — they are just looking for the next person to trick.

        Selection that feels too easy is not luck. It is a warning sign.

        Free Fake Job Offer Checker Tool: Check Any Job Instantly

        ScamDekho is India’s free fake job offer checker tool. You do not need to create an account. You do not need to download any app. Just paste the link and get your answer in seconds.

        How to Use ScamDekho to Check Any Job Offer Link

        Step 1 — Do Not Click the Link Directly

        Press and hold the job link in WhatsApp, Telegram, or SMS. Select “Copy Link.” This lets you check it safely without opening it.

        Step 2 — Open ScamDekho

        Go to scamdekho.in

        You will see the URL Checker tool right on the homepage. No login needed.

        Step 3 — Paste the Link and Hit Check

        Paste the copied job link into the checker box and click Check Now.

        ScamDekho instantly scans the link for:

        • Domain Age — Fake job sites are almost always less than 30 days old
        • Google Safe Browsing — Already reported scam links are flagged instantly
        • Phishing Database Match — Checked against thousands of known fraud links
        • SSL & Hosting Reputation — Whether the server is linked to fraud activity
        • Redirect Behaviour — Whether the link is hiding its real destination
        • IP Reputation — Whether the website is hosted on a known scam server

        Step 4 — Read Your Result

        ResultWhat It MeansWhat to Do
        SafeLink appears genuineStill verify company directly
        ScamConfirmed scam linkDelete message, report immediately

        Why ScamDekho? Most Indians click first and regret later. ScamDekho gives you the answer before you click — completely free, no technical knowledge needed, works on any device.

        Common Types of Job Scams in India

        It helps to know what you are up against. These are the most common job scams currently operating in India:

        • Data entry and work-from-home scams ask for an upfront payment for training or materials, then either disappear or provide work without ever paying for it.
        • Fake government job offers use official-looking documents, government logos, and formal language to appear legitimate. Many people fall for these because they carry an air of authority.
        • Call center job scams require you to pay for training sessions or ID cards before you can start work. The job never materializes.
        • Freelance scams involve getting real done from the victim and then refusing to pay, claiming issues with quality or disappearing entirely.
        • Overseas job scams promise well-paying jobs abroad but ask for visa fees, processing charges, or travel costs upfront. The job does not exist.

        How to Report Fake Job Scams in India

        If you come across a fake job offer — whether you fell for it or caught it in time — report it. Your report can prevent someone else from going through the same experience.

        You can file a complaint online at cybercrime.gov.in or call the cybercrime helpline at 1930. Both options are free and available to anyone in India.

        Reporting takes ten minutes. It could save someone else from losing their savings.

        Final Thoughts

        Fake job offers are getting more sophisticated every year. Scammers now use real company names, well-designed offer letters, and convincing email templates that are genuinely difficult to tell apart from the real thing.

        But the fundamentals have not changed. No real job requires payment. No legitimate company skips a proper interview. And no genuine recruiter pressures you to decide in a hurry.

        Take your time. Do your checks. And if something does not feel right — trust that instinct. Your career can wait a few days for verification. Your savings cannot afford to be lost to a scam.

      3. KYC Scam in India: Fake Bank Messages That Are Stealing Your Money

        KYC Scam in India: Fake Bank Messages That Are Stealing Your Money

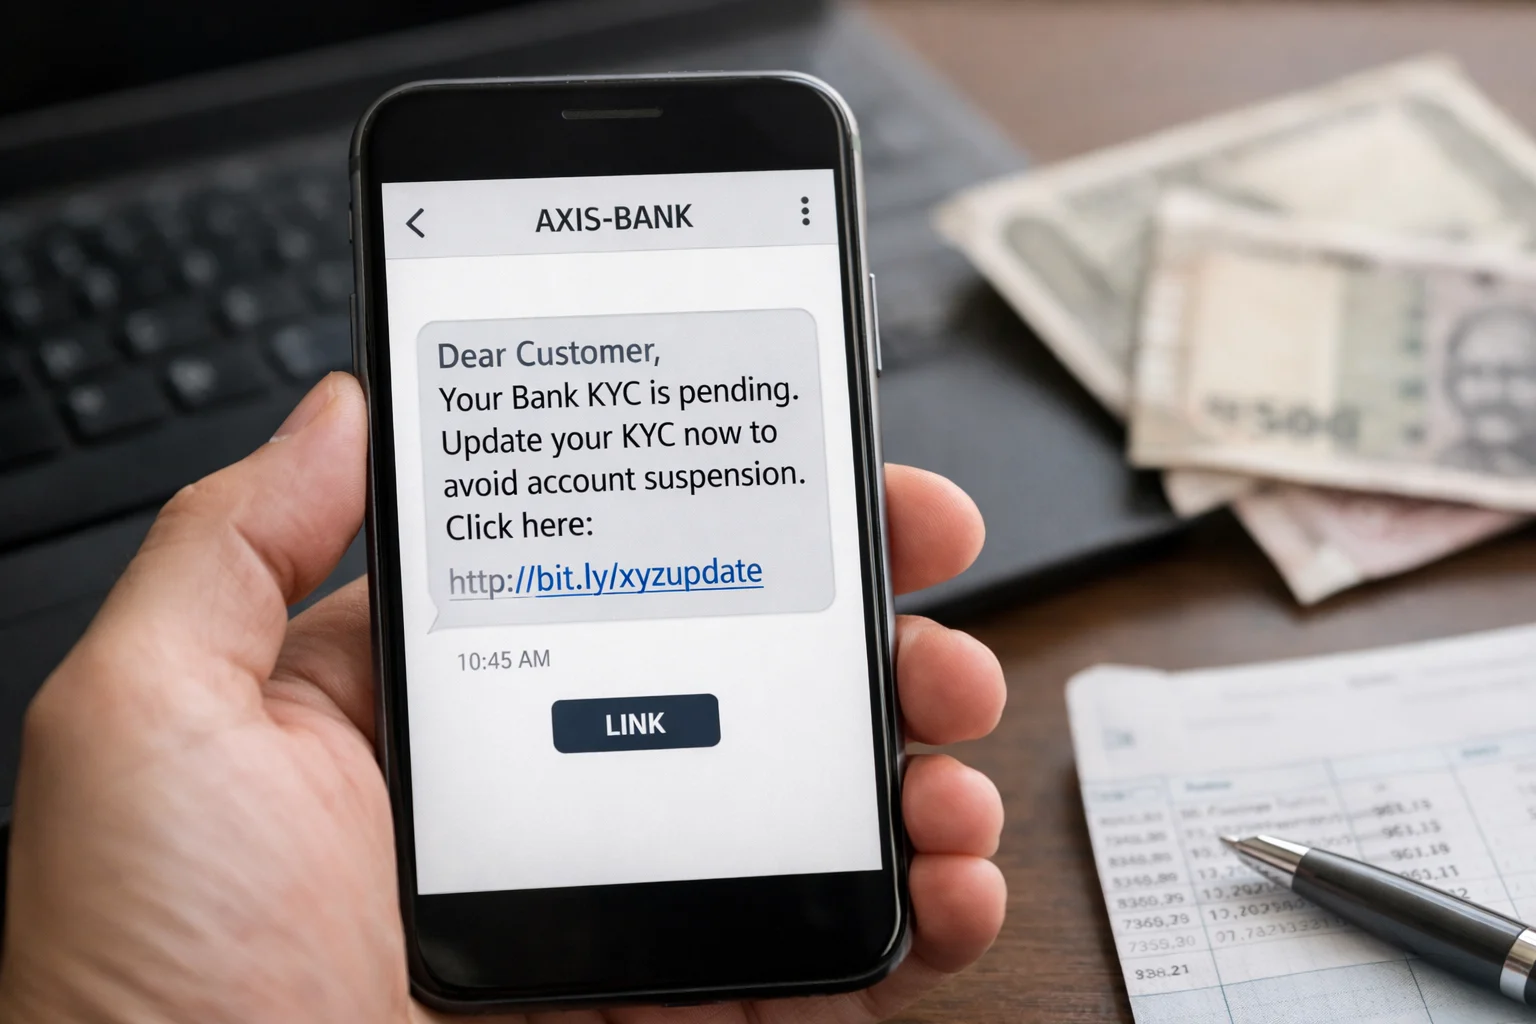
        Your phone buzzes. A message from what looks like your bank:

        “Dear Customer, your KYC is expired. Your account will be blocked within 24 hours. Click here to update now: bit.ly/kycupdate”

        You panic. Your salary gets credited to that account. Your EMIs are linked to it. You cannot afford to have it blocked.

        So you click.

        And within minutes, your life savings are gone.

        This is the KYC scam — and it is one of the biggest categories of cyber fraud in India, with 22.68 lakh cybercrimes reported in 2024 alone.

        What Is a KYC Scam?

        KYC stands for Know Your Customer. It is a real process that banks and financial apps use to verify your identity. Your Aadhaar, PAN, address proof — all of this is part of KYC.

        In a KYC scam, fraudsters pose as bank representatives or financial institution officials. They contact you with fake urgency — claiming your KYC has expired and your account will be suspended — to trick you into sharing sensitive personal and financial information. Facebook

        The scam works because it uses a real process that every Indian bank customer is familiar with. When you hear “KYC update,” you do not immediately think “scam.” You think “I need to do this.”

        That split second of trust is all the fraudster needs.

        How Big Is This Problem? Real Numbers

        According to the Indian Cyber Crime Coordination Centre (I4C), cyber fraud losses in India are projected to reach ₹1.2 lakh crore in 2025.

        KYC scams are specifically highlighted in the 2025 Digital Banking Fraud Trends report as one of the fastest-growing fraud categories — enabled by India’s rapid push toward digital financial services.

        Real Cases From Across India

        These are actual incidents reported by police and news outlets:

        1. Delhi — 8,000+ Victims, One Gang

        Delhi Police’s Intelligence Fusion and Strategic Operations unit busted a pan-India gang that looted over 8,000 victims across India. The gang sent bulk SMS messages claiming to be from SBI, asking people to update their KYC. They used a fake version of SBI’s YONO app to steal net banking credentials and transferred money to fake accounts. 23 people were arrested.

        2. Delhi — ₹8 Lakh Lost by One Victim

        A Delhi resident lost ₹8 lakh in a fake KYC scam where fraudsters posed as bank officials and convinced the victim to share sensitive financial details.

        3. Mumbai — ₹2 Lakh Stolen from 73-Year-Old Woman

        A 73-year-old woman in central Mumbai was duped of ₹2 lakh by cyber fraudsters who called her on the pretext of updating her bank KYC details.

        4. Mumbai — Actress Shweta Menon Among Victims

        Around 40 customers of a private bank in Mumbai — including actress Shweta Menon — lost money after receiving fake SMS messages asking them to update their KYC or PAN details. Shweta lost ₹57,636 after clicking the link and entering her bank credentials and OTP.

        Check: What Is a Digital Arrest Scam And How to Protect Yourself

        4 Types of KYC Scams You Must Know

        Fraudsters do not rely on just one method. Over time, they have developed several variations of the fake KYC scam — each one designed to exploit a different situation and a different type of victim. Here are the most common ones you need to know about.

        Type 1: Fake SMS With a Phishing Link

        This is the most widespread variation. You receive an SMS or WhatsApp message warning you that your KYC is incomplete and your account will be suspended if you do not update it immediately. The message includes a link that looks legitimate at first glance.

        But the link leads to a fake website — a near-perfect copy of your bank’s official portal. Once there, you are asked to enter your username, password, and OTP. The moment you do, the fraudster uses those credentials to log into your real account and transfer money out before you even realize what has happened.

        Type 2: The Fake Call and Remote Access Trap

        This is one of the most dangerous variations — and one of the hardest to recover from.

        A fraudster calls you, sounding professional and convincing, claiming to be from Paytm, SBI, or your bank’s customer support team. They tell you there is an urgent KYC issue with your account and ask you to download a remote access app like AnyDesk, TeamViewer, or QuickSupport to resolve it.

        Once you install the app and share the access code, the fraudster gains complete control of your phone. They can see your screen in real time — your OTPs, banking apps, saved passwords, and messages. Everything. From that point, draining your account takes only a few minutes.

        Type 3: Fake KYC App Sent as an APK File

        In this variation, the scammer sends you an APK file over WhatsApp or SMS, presenting it as an official app from your bank or payment platform. The file name and icon are designed to look legitimate.

        Once you install it, the fake app immediately requests permissions to access your SMS, contacts, calls, and banking apps. With those permissions granted, the fraudster has everything they need to monitor your activity and take over your accounts silently — without you noticing until the damage is done.

        It is worth noting that SBI has officially stated that it never asks customers to download any application from unofficial sources. If you receive such a request, it is a scam without exception.

        Type 4: Smishing — When SMS and a Phone Call Work Together

        Smishing takes a slightly different approach. You receive an SMS asking you to call a specific number to complete your KYC update. The message feels urgent and official, so you call.

        On the other end is a scammer posing as a bank representative — calm, polite, and knowledgeable enough to sound credible. Through the conversation, they gradually manipulate you into sharing your Aadhaar details, OTP, account passwords, and other sensitive information. By the time the call ends, they have everything they need.

        8 Warning Signs of a Fake KYC Message

        Before you do anything with a KYC message, check for these red flags:

        1. It creates urgency or threatens account block Real bank messages never use threatening language or harsh deadlines like “your account will be blocked today.” If the message panics you into acting fast, it is almost certainly fake.

        2. It Comes From a Random Number Official bank messages always arrive from registered sender IDs — not from a random 10-digit mobile number. Scammers sometimes manage to display a bank’s name as the sender, but look carefully at the actual number or ID. If it looks like a regular phone number, it almost certainly is not from your bank.

        3. The Link Looks Almost Right — But Not Quite
        Fake websites are built to look identical to the real thing. The only giveaway is usually the URL. Scammers register domains like sbi-kyc-update.com or paytm-verify.net — close enough to look real at a glance, but wrong on closer inspection. Before entering any details on a website, check the address bar carefully. One extra word, one hyphen, one different letter — and it is fake.

        4. It asks for OTP, PIN, or CVV
        There is no situation – none – where a real bank will ask for your OTP, ATM PIN, or card CVV. Not on a website, not over a call, not through SMS. This is a hard rule across every bank and payment platform in India. The moment someone asks for this information, stop and disconnect.

        5. It asks you to download an app from a link
        Banks publish their apps on the Google Play Store and Apple App Store. That is it. If someone sends you an APK file over WhatsApp or SMS and asks you to install it, delete it immediately. It does not matter how official it looks.

        6. It asks you to install AnyDesk or TeamViewer
        This is a major red flag. No bank will ever ask you to install a remote access app. If a caller — however polite or convincing they sound — asks you to install AnyDesk, TeamViewer, or QuickSupport and share a code with them, they are trying to take over your phone. Put the phone down.

        7. The message is generic — no account number or your name Real bank communications almost always include your name or partial account number for personalization. Generic messages like “Dear Customer” are a red flag.

        8. The link uses a URL shortener Legitimate banks never use bit.ly, tinyurl, or similar shortened URLs in official messages.

        Real vs Fake KYC Message — Quick Comparison

        FeatureReal KYC CommunicationFake KYC Scam
        SenderOfficial bank IDRandom number or spoofed ID
        ToneNeutral, informationalUrgent, threatening
        LinkOfficial bank website onlyShortened or lookalike URL
        Asks for OTP/PINNeverAlways
        Asks to download APKNeverVia WhatsApp or SMS
        Asks for AnyDesk/TeamViewerNeverAlways
        Has your nameUsually yesUsually “Dear Customer”

        Banks That Scammers Commonly Impersonate

        Scammers target customers of the most popular banks and apps. Be extra careful if you receive KYC messages claiming to be from:

        SBI, HDFC, ICICI, Axis Bank, and payment apps like Paytm are the most commonly impersonated institutions in fake KYC scams.

        If in doubt — call your bank directly using the number on the back of your card or on the official bank website. Never use a number given in any SMS.

        How to Update Your Real KYC Safely

        If you actually need to update your KYC, here is how to do it the right way:

        • Visit your bank branch in person This is the safest option. Carry your Aadhaar and PAN and get it done directly.
        • Use your bank’s official app Open the app you downloaded from Google Play or App Store — not any link sent by SMS.
        • Log in to your bank’s official website Type the URL yourself in the browser. Do not click any link from any message.

        How to Check If a KYC Message or Link Is Real or Fake

        Getting a KYC message and not sure if it is real? Do not guess. Follow these steps before you click anything.

        Step 1: Copy the Link From the Message

        Do not click it. Just press and hold the link in the SMS or WhatsApp message and copy it.

        Step 2 : Open ScamDekho URL Checker

        Go to: scamdekho.in

        Scroll down to the URL Checker tool on the homepage.

        Step 3: Paste the Link and Scan

        Paste the copied link into the URL checker box and hit Check.

        ScamDekho will instantly analyse the link for:

        • Domain age — fake sites are usually less than 30 days old
        • SSL certificate — whether the site is genuinely secure
        • Google Safe Browsing — whether it is already flagged as dangerous
        • Phishing database match — checked against known scam databases
        • Redirect behaviour — whether the link hides its real destination
        • Hosting reputation — whether the server is linked to fraud activity

        Step 4 — Read the Result

        ScamDekho will show you one of three results:

        ResultWhat It Means
        SAFELink appears genuine — still verify with your bank directly
        SCAMConfirmed scam link — delete the message immediately

        Step 5 — When in Doubt, Call Your Bank Directly

        Even if ScamDekho shows Safe — if the message is asking for OTP, PIN, or CVV — it is a scam. Call your bank on the number printed on the back of your debit or credit card.

        ScamDekho is completely free. No login needed. No app download needed. Just paste the link and get your answer in seconds.

        If You Already Fell for a KYC Scam — Do This Right Now

        Every minute counts. Take these steps immediately:

        1. Call your bank’s 24×7 helpline and block your card and freeze your account
        2. Change your net banking password and UPI PIN from a different device if possible
        3. Uninstall any app you downloaded from that link
        4. Call 1930 — National Cyber Crime Helpline — and report the fraud immediately
        5. File a complaint at cybercrime.gov.in
        6. Factory reset your phone if you installed an APK or gave AnyDesk access

        The faster you act, the better the chances of your money being recovered.

        Why Do Educated People Fall for This Scam?

        This is an important question. The victims of KYC scams are not uneducated or careless people. They are regular professionals, homemakers, and senior citizens.

        Scammers know exactly how to trick and manipulate people. They exploit urgency, authority, and fear — three things that short-circuit logical thinking even in intelligent people.

        When you believe your bank account is about to be blocked, you stop thinking clearly. You act fast. That is exactly what the fraudster designs the message to do.

        Conclusion

        The KYC scam is one of the most widespread and convincing cyber frauds targeting Indian bank customers today. It has taken ₹2 lakh from a 73-year-old woman in Mumbai, ₹8 lakh from a Delhi resident, and looted 8,000+ victims through a single organized gang.

        The most important thing to remember is this: Your bank will never send you a link to update your KYC. It will never ask for your OTP, PIN, or CVV. And it will never ask you to download an app from an SMS.

        If you receive any such message, ignore it. If you are unsure about a link, scan it on ScamDekho before clicking anything.

        Stay safe — and share this article with your family, especially with anyone who uses mobile banking.

      4. E-Challan Scam in India: How to Check Fake Traffic Challan Messages Easily

        E-Challan Scam in India: How to Check Fake Traffic Challan Messages Easily

        You get a message on your phone.

        “A traffic challan of ₹1,200 has been issued against your vehicle. Pay immediately to avoid licence suspension.”

        The message looks real. It has your vehicle number. It has an official-looking link. You are in a hurry, so you click.

        Within hours, your bank account is empty.

        This is the e-challan scam — and it is happening every single day across India in 2026.

        How Big Is This Problem? Real Numbers

        This is not a small or occasional fraud.

        In Maharashtra alone, 193 cyber fraud cases related to fake e-challan links and APK files were registered in 2025, and 36 accused were arrested.

        This is not just a metro city problem anymore. Victims in Delhi, Mumbai, Bengaluru, Chennai, and Hyderabad have reported losing thousands after clicking on fake e-challan links.

        The scale is growing. The scammers are getting smarter. And the victims are not just uneducated or elderly people — they are businessmen, shopkeepers, professionals, and daily vehicle owners.

        Real Cases From Across India

        These are actual police-reported incidents. Read them carefully — any one of these could happen to you.

        1. Vadodara, Gujarat — ₹34.75 Lakh Lost

        A businessman from Vadodara lost ₹34.75 lakh after installing a malicious app called RTO e-challan.apk that he received on WhatsApp. The app compromised his banking details and led to a series of unauthorised transactions.

        2. Nashik, Maharashtra — ₹6 Lakh Stolen

        A man from Nashik received a fake e-challan SMS with a link. He clicked it, and his personal banking details were stolen. ₹6 lakh was drained from his account.

        3. Rajkot, Gujarat — ₹10.81 Lakh Gone

        A shop owner in Rajkot downloaded a fake traffic challan app. The app silently accessed his banking data and ₹10.81 lakh was stolen.

        4. Coimbatore — ₹2.96 Lakh Lost

        Several residents in Coimbatore received fake traffic challan messages on WhatsApp asking them to download an app. One victim lost ₹2.96 lakh.

        5. Kochi — Two Scammers Arrested

        In Kochi, two suspects were arrested for spreading counterfeit Parivahan apps through WhatsApp. The fraud operation used a Telegram bot to gather vehicle information before targeting victims.

        What Is the E-Challan Scam? (Simple Explanation)

        In an e-challan scam, fraudsters pretend to be traffic authorities or RTO officials. They send fake messages through SMS or WhatsApp, claiming that you have violated a traffic rule and must pay a fine immediately. These messages often look completely legitimate, they include your vehicle number and a payment link that closely copies the government portal.

        The goal is simple panic you into clicking fast, without thinking.

        3 Types of E-Challan Fraud You Must Know

        1. Type 1 — Fake SMS or WhatsApp Link

        You receive a message saying you have a pending traffic fine and must pay immediately to avoid licence suspension. The link looks official, the logo seems real, and the urgency feels genuine. Once you click and enter your details, your money and data are gone.

        2. Type 2 — Fake Website (Phishing Portal)

        Clicking the link takes you to a cloned portal that mirrors the branding and structure of the real government e-Challan website — including the government logo, MoRTH references, and official branding. This is purely to convince you that the challan is real. When you click “Pay Now,” your card details go directly to the attacker’s server — whether the payment succeeds or not.

        3. Type 3 — Malicious APK App (Most Dangerous)

        This is the most dangerous version of the scam.

        Scammers distribute a fake RTO Challan Android app through WhatsApp, framing messages to look official with fabricated challan numbers, violation dates, and vehicle registration details. Once installed, the app harvests your Aadhaar, PAN, SIM data, phone numbers, and SMS contents, and silently intercepts your OTPs — giving attackers complete access to your financial accounts.

        8 Warning Signs of a Fake E-Challan

        Check for these red flags before you do anything:

        1. Sender is a random mobile number Real government messages come only from the official sender ID “VM-PARIVAHAN.” Fake ones come from random mobile or international numbers.

        2. Link does not end in .gov.in Real challan links end in .gov.in. Fake ones use .in, .co, .xyz, or shortened URLs.

        3. Message creates urgency or threats Real messages use a neutral tone. Fake ones use lines like “Pay in 2 hours or your licence will be suspended” to make you panic.

        4. Spelling mistakes or odd formatting Fake messages often have spelling errors, odd spacing, or inconsistent fonts.

        5. No vehicle number in message Real challans always mention your exact vehicle registration number. If it is missing — it is fake.

        6. Asks for OTP, ATM PIN, or CVV No government portal ever asks for your OTP, PIN, or card CVV. Ever. If it does — it is a scam.

        7. Asks you to download an APK No government department sends apps over WhatsApp or SMS. If you receive any APK file claiming to be an RTO app — delete it immediately.

        8. Payment only through card, not UPI Fake payment pages are deliberately restricted to credit or debit cards, avoiding traceable UPI or net banking methods — because cards are harder to trace.

        Also Read: Is This Link Safe? How to Check a Suspicious URL Before Clicking

        Real Challan vs Fake Challan — Quick Comparison

        FeatureReal e-ChallanFake e-Challan
        Sender IDVM-PARIVAHANRandom mobile number
        Website URLechallan.parivahan.gov.inFake lookalike domain
        Vehicle NumberAlways mentionedOften missing
        OTP / PIN askedNeverAlways
        APK sentNeverVia WhatsApp / SMS
        ToneNeutralUrgent, threatening
        Payment MethodUPI, card, net bankingOnly card

        How to Check Your Real E-Challan Safely

        If you think you may have a genuine pending challan, check it the safe way:

        1. Official Government Portal Go directly to “https://echallan.parivahan.gov.in” Type this URL yourself in your browser. Do not click any link from any message.
        2. mParivahan App Download the official mParivahan app from Google Play Store or Apple App Store only.
        3. Scan Suspicious Links on ScamDekho Before clicking any challan link, paste it into ScamDekho’s free URL checker to instantly find out if it is safe or a scam.

        If You Already Clicked a Fake Link — Do This Right Now

        Act fast. Every minute matters.

        1. Do not enter any more details on that website if you have not already
        2. Call your bank immediately on their 24×7 helpline — block your card and freeze transactions
        3. Change your net banking password and UPI PIN right now
        4. Uninstall any app you may have downloaded from that link
        5. Call 1930 — National Cyber Crime Helpline — and report the fraud
        6. File a complaint online at cybercrime.gov.in
        7. Consider a factory reset if you installed an APK from that link

        Why Do People Fall for This Scam?

        This is an important question — because the victims are not foolish people.

        These are not random phishing attempts. They are professionally designed and organised frauds built to look exactly like actual government portals, complete with Parivahan branding, state police websites, and even fake customer care numbers.

        The scam works because it exploits two things every vehicle owner has fear of legal action and trust in government systems.

        When you see a government logo and a threat of licence suspension, your brain skips the verification step. That is exactly what the scammers count on.

        Conclusion

        The e-challan scam is one of the fastest-growing cyber frauds in India in 2025. It has taken ₹34 lakh from a businessman in Vadodara, ₹6 lakh from a man in Nashik, and ₹10 lakh from a shopkeeper in Rajkot — all from a single SMS or WhatsApp message.

        The rule to remember is simple: The Indian government never sends payment links over SMS or WhatsApp. Never.

        If you get any challan message, always verify directly on echallan.parivahan.gov.in — and if a suspicious link has already reached you, scan it first on ScamDekho before you click anything.

        Stay safe. And share this article — one share can protect someone you know from losing their life savings.

      5. AI Voice Cloning Scam in India: When the Caller Sounds Exactly Like Your Family Member

        AI Voice Cloning Scam in India: When the Caller Sounds Exactly Like Your Family Member

        Your phone rings. You answer. It is your son’s voice — panicked, crying: “Papa, I have been in an accident. I am in the hospital. Please send money immediately. Do not tell anyone.”

        The voice is perfect. The fear is real. You transfer ₹50,000 within minutes.

        Then your son calls from his actual number — safe at home, having no idea what just happened.

        This is the AI voice cloning scam. And in 2026, scammers need just 3 seconds of your family member’s voice — taken from an Instagram Reel, a WhatsApp voice note, or a YouTube video — to clone it so accurately that even you cannot tell the difference.

        In this guide, we explain exactly how this scam works, how scammers steal your voice without you knowing, real cases from India, and the one protection method that no AI can defeat.

        How Serious Is This Threat in India?

        • 3 seconds of audio is all a scammer needs to clone any voice in 2026 — down from 20 minutes just three years ago
        • 47% of Indian adults have personally experienced an AI voice cloning scam or know someone who has — nearly double the global average
        • 77% of voice cloning victims globally lost money as a result of the scam
        • ₹2.3 crore was lost by a Mumbai company when a CFO authorised a wire transfer after receiving a call from a cloned CEO voice in early 2026
        • Global losses from deepfake and voice cloning fraud exceeded $200 million in just Q1 of 2025 — and India accounts for 8% of all cases
        • 70% of people worldwide say they are not confident they could tell the difference between a cloned voice and the real thing

        The technology is advancing faster than human detection. And scammers in India are already using it daily.

        How Does AI Voice Cloning Work?

        You do not need to understand the technology in detail — but understanding the basics helps you realise how serious this threat is.

        Step 1: Scammer Finds Your Voice

        Scammers havest voice samples from publicly available sources. They do not need to hack your phone or intercept your calls. They look for:

        • Instagram Reels and Stories where you speak
        • YouTube videos — even short ones
        • WhatsApp Status videos with voice
        • Facebook videos and Live sessions
        • Podcasts, interviews, or news clips
        • Voice notes that were accidentally made public

        Step 2: AI Clones the Voice in Minutes

        Using freely available AI tools, the scammer uploads the 3-second audio clip. The AI extracts a “voice fingerprint” — capturing the exact tone, pitch, rhythm, and emotional quality of the person’s voice. Within minutes, the scammer can type any text and the AI will speak it in that person’s voice — complete with emotion, urgency, and natural breathing patterns.

        Step 3: The Call Is Made

        The scammer calls a family member — usually a parent, spouse, or sibling. The call appears to come from an unknown number, and the cloned voice immediately creates panic. The script almost always includes:

        • A sudden emergency — accident, arrest, hospital, or robbery
        • A request to send money immediately via UPI
        • A demand not to tell anyone or call back on the regular number
        • Extreme urgency — “There is no time, please send now”

        The emotional shock of hearing a loved one’s voice in distress bypasses rational thinking. Most victims transfer money before even considering whether the call might be fake.

        Types of AI Voice Cloning Scams in India

        1. Family Emergency Scam

        The most common variant. A parent receives a call from a cloned child’s voice claiming to be in a hospital, jail, or accident. They are asked to immediately transfer money — and told not to call back on the regular number because “the phone is damaged” or “I am in police custody.”

        2. Virtual Kidnapping Scam

        Scammers clone a child’s voice screaming or crying and call parents claiming they have kidnapped the child. They demand a ransom — ₹50,000 to ₹5 lakh — to be transferred immediately. Meanwhile, the child is perfectly safe somewhere with their phone on silent or unavailable. Scammers time these calls carefully.

        3. CEO and Boss Fraud

        A company employee receives a call from what sounds exactly like the CEO or MD — asking them to urgently transfer funds to a specific account. The voice is cloned from public videos, conference recordings, or media appearances. A Mumbai CFO lost ₹2.3 crore in exactly this scenario in early 2026.

        4. Friend in Need Scam

        A cloned voice of a close friend calls claiming to be stranded — abroad, in another city, or in a difficult situation — and asks for an urgent UPI transfer. “I will explain everything later, just please help me now.”

        5. Government Officer Impersonation With Voice

        Combined with digital arrest scams, scammers now use AI-cloned voices of judges, police officials, or government officers to make fake arrest or legal threat calls sound more convincing and authoritative.

        Real Cases

        Case 1 — Mumbai, Maharashtra — ₹2.3 Crore Lost

        A CFO at a Mumbai company received a phone call from a voice that sounded exactly like the company’s CEO — asking for an urgent wire transfer for a critical business payment. The voice passed every mental credibility check. The CFO authorised ₹2.3 crore. The CEO was in a meeting the entire time and had made no such call. The voice was AI-generated using publicly available recordings of the CEO from company events.

        Case 2 — Lucknow, Uttar Pradesh — ₹47,000 Lost

        A retired teacher from Lucknow received a call from a voice that sounded exactly like her son. He was “in an accident on the highway” and needed ₹47,000 urgently for hospital admission. She transferred the money immediately. When she called her son’s regular number, he picked up — he was at the office and had no idea. By the time she realised what happened, the UPI transfer was already processed.

        Case 3 — Bengaluru, Karnataka — ₹1.2 Lakh Lost

        A software professional received a call from what sounded like his close friend — claiming to be stranded in Delhi after a robbery and needing ₹1.2 lakh for a flight back. His friend’s voice, his friend’s manner of speaking, even his friend’s nickname for him were replicated accurately. The scammer had harvested audio from the friend’s Instagram Reels and used additional personal details found on social media.

        Case 4 — Hyderabad, Telangana — Virtual Kidnapping

        Parents of a college student received a call with their daughter’s voice screaming and crying — saying she had been kidnapped and kidnappers were on the line. The parents were told to transfer ₹3 lakh immediately and not call the police. They were about to transfer when a neighbour suggested they try calling their daughter’s phone from a different number. She picked up — completely safe in her college hostel. The entire call was fabricated using 4 seconds of audio from her Instagram Story.

        How Scammers Steal Your Voice Without You Knowing

        You do not have to do anything wrong for your voice to be stolen. Scammers harvest voice data from:

        • Public Instagram Reels and Stories — the most common source. Even a 5-second clip of you speaking is enough
        • YouTube videos — any video where you appear speaking
        • WhatsApp Status videos — if your privacy is set to “My Contacts” or “Everyone”
        • Facebook videos and Lives — especially older videos that were made public
        • Podcasts and webinars — professional appearances are prime targets
        • News interviews and college recordings — any publicly available audio

        If you have ever spoken in a video posted publicly online — your voice can be cloned today. This is not a future threat. It is happening right now.

        How to Detect an AI Cloned Voice Call

        Current AI voice cloning is 95% accurate — but not perfect. Here is what to listen for:

        • Unnatural rhythm: AI voices often have a perfectly uniform pace — too even, too smooth. Real distressed voices crack, speed up, and slow down irregularly
        • Unusual background: Real emergency calls have chaotic background noise — traffic, hospital sounds, voices. Cloned audio is often suspiciously clean or has a faint digital hiss
        • Avoids specific questions: Ask something only the real person would know — a pet’s name, a family joke, a recent private conversation. AI cannot answer from a voice clone alone
        • Refuses video call: If the caller refuses to switch to video or FaceTime, that is a major red flag
        • Extreme urgency: Scammers use urgency to prevent you from thinking clearly. Real emergencies allow time to verify

        The One Protection That No AI Can Defeat — Family Code Word

        This is the single most effective protection against AI voice cloning scams. Set up a family safe word right now — today, before you finish reading this article.

        How to Set It Up

        1. Choose a random word that has no obvious connection to your family — not a pet’s name, not a hometown, not a favourite food. Something unexpected like “mango tree” or “blue kite” or “seven stairs”
        2. Share this word privately with all immediate family members — in person or on an encrypted message that you then delete
        3. Make a family rule: anyone claiming to be a family member in an emergency must say the code word before any money is sent
        4. If the caller cannot provide the code word — hang up immediately and call the family member directly on their regular number
        5. Change the code word every few months

        No AI voice clone can say your family’s secret code word because it does not exist in any audio or public data. This one simple step defeats even the most advanced voice cloning technology available today.

        7 Things to Do Right Now to Protect Yourself

        • Set a family code word today — share it with all immediate family members privately
        • Review your social media privacy settings — make old videos private or friends-only on Instagram and Facebook
        • Never send money based on a voice call alone — always verify by calling back on the person’s regular number
        • Tell your parents and elderly relatives about this scam — they are the most likely targets of family emergency variants
        • If you receive such a call — hang up and call back on the saved number. Do not use any number the caller gives you
        • Never trust urgency — “send money right now or it will be too late” is always a manipulation tactic, not a real emergency
        • Report suspicious calls on Sanchar Saathi at sancharsaathi.gov.in and file at cybercrime.gov.in

        What to Do If You Already Sent Money

        1. Call 1930 Immediately

        India’s National Cybercrime Helpline is available 24×7. Call as soon as you realise the fraud. Cyber cells can attempt to freeze the beneficiary UPI account before funds are moved further. Every minute matters.

        2. File at cybercrime.gov.in

        File a complaint under “Online Financial Fraud.” Include the caller’s number, UPI ID you sent money to, transaction UTR number, and approximate time of the call.

        3. Contact Your Bank

        Call your bank’s fraud helpline immediately. Provide the UTR number of the fraudulent transaction and request an emergency freeze on the beneficiary account.

        4. Report the Number on Sanchar Saathi

        Go to sancharsaathi.gov.in → Chakshu → report the phone number used by the scammer. This helps authorities trace and block serial fraud numbers.

        5. File an FIR

        Visit your nearest cyber police station with all evidence — the caller’s number, UPI transaction receipt, and a written account of what happened. File under Section 318(4) of BNS 2023 and Section 66D of the IT Act.

        Check: How to Report a Cyber Crime in India: Complete Step-by-Step Guide (2026)

        Key Takeaways

        • AI voice cloning needs just 3 seconds of audio — available from any public video or Reel
        • 47% of Indian adults have experienced or know someone who faced this scam
        • Scammers create family emergencies, virtual kidnappings, and boss fraud calls using cloned voices
        • 77% of people who received a voice clone call lost money as a result
        • Set a family code word today — it is the only protection AI cannot defeat
        • Never send money based on a voice call alone — always call back on the saved number
        • If scammed, call 1930 immediately — every minute matters for fund recovery

        Conclusion

        The most terrifying thing about AI voice cloning scams is not the technology — it is how it exploits the most human of instincts. When you hear someone you love in distress, you do not think. You act. You help. That is exactly what scammers count on.

        But now you know. You know how they steal the voice. You know how the call is made. You know what to listen for. And most importantly — you know about the family code word, the one protection that no AI tool in the world can defeat.

        Set it up today. Right now. Call your parents, your spouse, your children — and agree on a word. It takes five minutes and could save lakhs.

        Share this article with everyone in your family. The elderly are most vulnerable to family emergency variants. Young people are most likely to have their voices harvested from social media. Everyone needs to know about this scam.

        And if you ever receive a suspicious link, a fake website, or an unknown UPI ID as part of any scam — check it for free on ScamDekho before clicking or paying.

        Set the code word. Verify before you pay. Share this with your family today.

        Frequently Asked Questions

        1. Can AI really clone a voice from just 3 seconds of audio?

        Yes. In 2026, AI tools like Microsoft’s VALL-E 2 and similar models can generate a convincing voice clone from as little as 3 seconds of clean audio. The AI extracts a voice fingerprint — capturing tone, pitch, rhythm, and emotional quality — and can then speak any text in that person’s voice. This technology is now freely available online.

        2. How do I know if the call I received was AI-generated?

        Listen for unnaturally smooth rhythm, suspiciously clean background noise, and evasiveness when asked specific personal questions. But the most reliable method is not to try to detect it — just always verify by calling back on the regular saved number of the person, regardless of how real the voice sounds.

        3. My social media is set to friends only. Am I safe?

        Safer — but not completely safe. Voice notes sent on WhatsApp, old public posts, group recordings, and content shared by mutual contacts can still be accessed. The safest approach is to assume your voice is accessible and focus on verification protocols rather than trying to completely prevent voice harvesting.

        4. Is the family code word really effective?

        Yes — it is the single most effective protection available. An AI voice clone can replicate how someone sounds but cannot know a privately shared secret word. As long as the code word is kept private and never mentioned in any public recording, no voice cloning technology can defeat it.

        5. Can companies protect themselves from CEO voice cloning fraud?

        Yes. Companies should implement multi-person authorisation for any financial transfer above a set amount, require written confirmation via official email for all fund transfers regardless of verbal instructions, and train finance teams to always verify unusual payment requests through a known secondary contact — never using contact details provided in the suspicious call itself.

      6. Pig Butchering Scam in India: How Fake Trading Apps Stole ₹14,000 Crore

        Pig Butchering Scam in India: How Fake Trading Apps Stole ₹14,000 Crore

        You get a WhatsApp message from an unknown number. Wrong number, it seems. The person is friendly. Educated. Well-spoken. Over the next few days, they become a trusted contact — sharing life updates, investment insights, and eventually, an opportunity that sounds too good to pass up.

        Three months later, your life savings are gone.

        This is the pig butchering scam — and it is now one of the most financially destructive cyber frauds operating in India. The name comes from a brutal analogy: scammers “fatten the pig” with trust and attention before “slaughtering” it and stealing everything.

        In this complete guide, we explain exactly what the pig butchering scam is, how it specifically targets Indians on WhatsApp and Telegram, real victim cases, fake trading apps used in India, and the exact steps to verify any investment opportunity before you put in a single rupee.

        What Is the Pig Butchering Scam?

        The pig butchering scam — also known as “Sha Zhu Pan” (杀猪盘) in Chinese — is a sophisticated long-term fraud that combines romance manipulation, fake investment platforms, and psychological pressure to steal large sums of money.

        Unlike most scams that try to steal money quickly, pig butchering scammers are patient. They spend weeks or months building a genuine emotional connection with the victim before introducing the investment trap. By the time money is requested, the victim trusts the scammer completely — making this one of the hardest scams to detect and resist.

        Key difference from other scams: Most scams steal small amounts from many people quickly. Pig butchering targets fewer people but steals far more — often lakhs or crores from a single victim.

        How Big Is This Problem in India?

        • Investment fraud — driven primarily by pig butchering — accounts for 76% of all money lost to cyber fraud in India
        • ₹14,000 crore was lost to investment and trading scams in India in 2024 alone
        • The Ministry of Home Affairs confirmed pig butchering complaints via WhatsApp, Telegram, Instagram, Facebook, YouTube, and Google Ads
        • An Indian IT professional lost $450,000 (approx. ₹3.7 crore) after being targeted on a dating app by a scammer using deepfake videos
        • Globally, pig butchering caused $12.4 billion in losses in 2023 — making it the world’s most financially damaging scam category
        • Scam centres operating from Myanmar, Cambodia, and Dubai specifically run India-targeted operations in Hindi, Tamil, Telugu, and other regional languages

        How the Pig Butchering Scam Works in India — Step by Step

        Stage 1: The First Contact (The Hunt)

        The scam begins with an innocent-seeming message. Scammers use multiple entry points:

        • Wrong number message: “Hi, is this Rahul? Sorry, wrong number!” — then continues the conversation naturally
        • WhatsApp/Telegram group invite: Added to a “premium investment group” with professional branding
        • Dating app match: An attractive profile on Tinder, Bumble, or Hinge — often using AI-generated or stolen photos
        • Instagram/LinkedIn DM: Posing as a business professional, NRI, or successful investor
        • Facebook or YouTube ad: Fake testimonials for a high-return investment platform

        Scammer profiles are carefully constructed. They use stolen photos, detailed backstories, lifestyle posts, and even fake social networks of “friends and family” who interact on their profiles to appear real.

        Stage 2: Building Trust (Fattening the Pig)

        This is the most time-consuming stage — and what makes pig butchering different from all other scams. The scammer spends days or weeks building a genuine emotional connection:

        • Daily good morning and good night messages
        • Sharing personal stories, photos, life updates
        • Asking about your life, family, work, and dreams
        • Casually mentioning their own financial success without pushing anything
        • In romance variants — developing deep emotional and sometimes romantic feelings

        By the end of this stage, you genuinely like and trust this person. You have no reason to suspect them. That is the point.

        Stage 3: The Investment Introduction

        Gradually, naturally, the scammer mentions investments. Not as a pitch — as a casual share. “My uncle works at a trading firm and gave me a great tip last week — I made ₹80,000.” They show you screenshots. They are not pushy. They say you do not have to invest if you do not want to.

        You ask about it. They guide you — slowly, patiently — to a trading group on WhatsApp or Telegram, or directly to a fake app.

        Stage 4: The Fake Trading Platform

        You are asked to download a trading app — usually via a direct link, not the Play Store. The app looks completely professional. It shows:

        • Live stock prices and crypto charts
        • Your portfolio with growing returns
        • Other members’ profit notifications
        • Customer support chat
        • Withdrawal history showing others receiving payments

        You invest a small amount — ₹5,000 or ₹10,000. The app shows a 15% profit the next day. You withdraw it successfully. It works. Confidence builds.

        Stage 5: Increasing Investments (The Slaughter Begins)

        The scammer encourages you to invest more. You invest ₹50,000. Then ₹2 lakh. Then ₹10 lakh. The app keeps showing profits. Group members are celebrating. The “expert” tells you that you have a gift for trading. A special IPO opportunity is coming — you need to invest more to access it. You borrow from family. You take a loan. You invest your retirement savings.

        Stage 6: The Withdrawal Block (The Slaughter)

        You try to withdraw. The app says you need to pay a 5% “capital gains tax” first. You pay it. Then a “SEBI compliance fee.” Then a “foreign remittance clearance charge.” Then one final “GST payment.” Every fee you pay, another one appears. The balance in the app keeps showing crores. But you can never access it. Then — the app goes offline. The scammer’s number is switched off. The Telegram group disappears. Everything is gone.

        Real Victim Cases in India

        Case 1 — Indian IT Professional, Philadelphia — ₹3.7 Crore Lost

        An Indian IT professional working in Philadelphia was targeted on a dating app by a scammer posing as a French wine trader. Using deepfake videos and scripted emotional manipulation, the scammer built an intense romantic connection over weeks. He gradually persuaded her to invest in fake cryptocurrency platforms. She ultimately lost more than $450,000 — leaving her in crushing debt with no way to recover funds sent abroad.

        Case 2 — Mumbai, Maharashtra — ₹1.23 Crore Lost

        A 49-year-old project manager was added to a WhatsApp group called “W1001-ACME Wealth Private Limited Group.” A woman named Priyanka guided him on trading strategies and had him download the fake “ACME Wealth” app. His initial ₹1 lakh investment showed 10% profit the next day. A fake SEBI certificate was provided for credibility. When he tried to withdraw ₹9 crore shown in the app, he was asked for a 5% “tax.” Total real loss: ₹1.23 crore.

        Case 3 — Hyderabad, Telangana — ₹5.9 Crore Lost

        A businessman received a message promoting a “Goldman Sachs Business School” for block trading. A woman posing as the Goldman Sachs MD’s assistant presented a fake SEBI-certified opportunity. He downloaded a fake trading app called “GSIN” and invested ₹5.9 crore across multiple transactions. When he tried to withdraw, a 20% “access fee” was demanded. He had lost everything.

        Case 4 — Faridabad, Haryana — ₹7 Crore Lost

        A woman was lured through a fake investment app promoted via social media. She was added to a WhatsApp group named “ICICI IR Team” where fake success stories were posted constantly. She invested her savings over several months. An ED investigation later found her ₹7 crore had been converted to cryptocurrency and sent abroad through shell company accounts.

        Case 5 — Hyderabad, Telangana — ₹71.11 Lakh Lost

        A private sector employee received a WhatsApp link on Christmas Day inviting him to a Telegram group associated with a “multinational financial services company.” Fraudsters created a fake internal equity account using his Aadhaar details. The portal showed a balance of ₹2.20 crore. When he tried to withdraw, all access was blocked. Total real loss: ₹71.11 lakh.

        Fake Trading Apps and WhatsApp Groups Used in India

        These apps and group names have been documented in police FIRs and ED investigations across India:

        Fake Trading Apps

        • ACME Wealth — Mumbai ₹1.23 crore case (2026)
        • GSIN — Goldman Sachs impersonation, Hyderabad ₹5.9 crore case
        • IC ORGAN MAX — ED investigation, multiple crore losses
        • EltAs Fud — Hyderabad arrest case
        • Costa Well Grown — ₹43 lakh victim losses
        • NFM Capital Markets — Hyderabad police complaint

        Fake WhatsApp Group Names

        • ICICI IR Team
        • Goldman Sachs Business School
        • BlackRock Stock Club
        • JP Morgan Investment Group
        • W1001-ACME Wealth Private Limited Group
        • GFSL Securities Official Stock C 80
        • SMG Global Securities

        None of these groups are affiliated with the real companies they impersonate. ICICI, Goldman Sachs, BlackRock, and JP Morgan do not recruit investors or share tips through WhatsApp or Telegram.

        How Pig Butchering Targets Indians Specifically

        Scam centres operating from Myanmar, Cambodia, and Dubai have dedicated India teams. Here is how they personalise attacks for Indian victims:

        • Communicating in Hindi, Telugu, Tamil, Kannada, or the victim’s regional language
        • Referencing Indian cities, landmarks, Bollywood, cricket, and local culture to build familiarity
        • Targeting NRIs with stories about overseas investment opportunities
        • Using Indian names, Indian stock market terminology, and SEBI branding
        • Impersonating Indian banks — ICICI, HDFC, SBI — and Indian brokers like Zerodha and Angel One
        • Timing attacks around IPO seasons, budget announcements, and festive periods when investment interest is high

        Warning Signs — How to Identify a Pig Butchering Scam

        • You received a message from an unknown number — wrong number, networking invite, or random introduction
        • The person quickly becomes close but avoids video calls or meeting in person
        • They casually mention their investment success without pushing you to invest
        • They guide you to a specific trading app or WhatsApp group
        • The trading app was sent via a direct link — not downloaded from Play Store or App Store
        • Early investments show immediate, impressive returns
        • You are encouraged to invest more — “a special IPO window is closing”
        • Withdrawal is blocked by demands for taxes, fees, or compliance charges
        • Reverse image search of their photo shows it belongs to someone else
        • The app shows a large balance that keeps growing but can never be withdrawn

        How to Verify Any Investment Before You Put In Money

        1. Check SEBI Registration at sebi.gov.in

        Every legitimate broker and investment advisor in India must be registered with SEBI. Go to sebi.gov.in → Intermediaries → search the platform or broker name. If it is not listed — do not invest. Any SEBI certificate sent via WhatsApp can be fabricated in minutes and means nothing.

        2. Only Use Official App Store Downloads

        Never download a trading app from a WhatsApp or Telegram link. All legitimate trading apps — Zerodha, Groww, Upstox, Angel One — are on the official Play Store and App Store. A link-only app is always fake.

        3. Do a Reverse Image Search

        Take the profile photo of the person who contacted you and run a reverse image search on Google Images or TinEye. If the photo belongs to someone else — model, stock photo, or real person — the account is fake. This takes 30 seconds and immediately exposes most pig butchering scammers.

        4. Verify the Company on MCA Portal

        Check the company at mca.gov.in → MCA Services → View Company/LLP Master Data. Check registration date and director details. Most fake companies were registered days before they contacted you.

        5. Never Pay Fees to Withdraw Your Own Money

        No legitimate broker, trading platform, or investment firm charges fees to withdraw your own money. Any withdrawal fee — tax, GST, SEBI compliance, foreign remittance — is a scam signal. Stop all payments immediately and call 1930.

        6. Check the Website on ScamDekho

        Before registering on any investment platform, check the website URL on ScamDekho. ScamDekho checks domain age, SSL certificate, hosting reputation, and known fraud databases. Fake investment websites are almost always registered less than 30 days before they contact you. Free, no login required.

        Legitimate SEBI-Registered Brokers in India

        Only use these verified platforms for stock market investments:

        • Zerodha — zerodha.com
        • Groww — groww.in
        • Upstox — upstox.com
        • Angel One — angelone.in
        • 5paisa — 5paisa.com
        • ICICI Direct — icicidirect.com
        • HDFC Securities — hdfcsec.com
        • Kotak Securities — kotaksecurities.com

        None of these will contact you via WhatsApp with tips, add you to Telegram groups, or ask you to download an app via a link.

        Already Scammed? Do This Immediately

        1. Call 1930 Right Now

        India’s National Cybercrime Helpline, available 24×7. Call immediately — cyber cells can attempt to freeze beneficiary accounts within hours of the fraud. Every minute counts.

        2. File at cybercrime.gov.in

        File under “Online Financial Fraud” → “Investment Fraud.” Include all app screenshots, chat screenshots, UPI transaction IDs, and any fake SEBI certificates or documents received.

        3. Contact Your Bank

        Call your bank’s fraud helpline with your UTR numbers for each transfer. Request emergency flagging of all beneficiary accounts. Provide your 1930 acknowledgement number and cybercrime.gov.in reference number.

        4. Report to SEBI

        Report the fake broker or platform at scores.gov.in or call SEBI helpline 1800-266-7575. SEBI issues public warnings about unregistered entities — your report protects others.

        5. File an FIR

        Visit your nearest cyber police station. File under Section 318(4) of BNS 2023 (cheating) and Section 66D of the IT Act (cheating using computer resources). Bring all printed evidence.

        Key Takeaways

        • Pig butchering is India’s most financially damaging cyber scam — responsible for 76% of all money lost to cyber fraud
        • Scammers spend weeks building genuine trust before introducing any investment
        • Fake trading apps show fabricated profits — the balance you see is never real money
        • Entry points include WhatsApp, Telegram, Instagram, dating apps, and Google Ads
        • Any withdrawal fee — tax, GST, compliance — is always a scam signal. Stop immediately.
        • Always verify SEBI registration at sebi.gov.in before investing anywhere
        • Never download a trading app from a WhatsApp link — only official app stores
        • Check any investment website on ScamDekho before registering
        • If scammed, call 1930 immediately — every hour reduces recovery chances

        Conclusion

        The pig butchering scam works because it targets something no security software can protect — human trust. It does not hack your phone. It does not steal your OTP. It makes you want to invest. And by the time you realise what happened, months of emotional investment and lakhs of rupees are already gone.

        But awareness is the only protection that works. Now you know the six stages. You know the warning signs. You know how to verify any investment in under five minutes. And you know that any fee to withdraw your own money is always — without exception — a scam.

        Before you invest in any online platform — no matter how trusted the person who recommended it — take 30 seconds and check the website on ScamDekho. It is free, requires no login, and could save you crores.

        Share this article with people in your life who invest online, use dating apps, or are active in investment WhatsApp groups. One conversation could protect someone’s life savings.

        Verify first. Invest safely. Trust no app from WhatsApp.

        Frequently Asked Questions

        1. What is a pig butchering scam in simple words?

        A pig butchering scam is when someone befriends you online over weeks or months, builds genuine trust, then convinces you to invest in a fake trading platform. The platform shows fake profits to encourage more investment. When you try to withdraw, it is always blocked. Then the scammer disappears with all your money.

        2. How is pig butchering different from other investment scams?

        Most investment scams move fast — they push you to invest immediately. Pig butchering is slow and patient. Scammers spend weeks building real emotional trust before mentioning money. This makes it far more effective and far harder to detect, because by the time the investment is introduced, you genuinely trust the person.

        3. Can pig butchering happen to educated people?

        Yes — and it frequently does. Victims include IT professionals, doctors, chartered accountants, engineers, and retired executives. Pig butchering exploits trust and emotion — not ignorance. Anyone who has human relationships is vulnerable. Education provides no protection against emotional manipulation.

        4. Is the trading WhatsApp group I was added to real?

        Almost certainly not, if you were added without asking. Legitimate SEBI-registered brokers do not add people to WhatsApp groups and share stock tips. Real trading is done through official apps on verified platforms. Any unsolicited WhatsApp trading group should be left immediately.

        5. Can I recover money lost in a pig butchering scam?

        Recovery is extremely difficult once funds are converted to cryptocurrency and sent abroad. However, if you call 1930 within hours of the fraud, cyber cells can attempt to freeze domestic accounts before funds move. File at cybercrime.gov.in immediately, contact your bank, and file an FIR. Do not pay any “recovery agent” — that is a third scam targeting the same victim.

      7. How to Report a Cyber Crime in India: Complete Step-by-Step Guide (2026)

        How to Report a Cyber Crime in India: Complete Step-by-Step Guide (2026)

        You just realised you have been scammed. Money is gone. You are panicking. You do not know what to do first.

        Take a breath. Then read this.

        Every minute matters after a cyber fraud. The faster you report, the better your chances of getting your money back. India has a proper system for this — most people just do not know how to use it.

        This guide gives you the exact steps to follow, the exact things to say to your bank, and the exact portals to file your complaint — all in one place, in simple language.

        How Serious Is Cyber Fraud in India Right Now?

        Before we get into the steps, here is why acting fast is so important:

        • ₹22,845 crore was lost to cyber fraud in India in 2024 — a 206% increase from 2023
        • 22.68 lakh complaints were filed on cybercrime.gov.in in 2024 — up from 10.29 lakh in 2022
        • National recovery rate improved from 10% in 2024 to 24% in 2025 — because more people are reporting faster
        • ₹4,386 crore has been saved so far through the 1930 helpline system by freezing fraudulent accounts in time
        • Only 1 in 10 cyber fraud victims in India actually report the crime

        The system works — but only if you use it fast enough.

        The Golden Rule: Report Within 24 Hours

        When you transfer money via UPI, NEFT, or any digital method — scammers move it through multiple accounts within minutes. The 1930 helpline system is directly connected to banks and can request an emergency freeze on the beneficiary account. But this only works if funds have not yet been moved or withdrawn.

        • 0 to 4 hours: Best chance of recovery — account freeze is very likely
        • 4 to 24 hours: Still possible — partial recovery realistic
        • 24 to 72 hours: Difficult — money has usually moved through multiple accounts
        • After 72 hours: Recovery is rare — but filing a complaint is still essential for legal record and bank dispute

        Do not wait. Do not feel ashamed. Do not think the amount is too small. Report immediately.

        What You Need Before You Start

        Keep all of this ready before making any call or filing any complaint. This will speed up the process significantly:

        Transaction Details

        • Exact amount lost and date and time of transaction
        • UTR number or Transaction ID (found in your UPI app or bank statement)
        • UPI ID, account number, or phone number you sent money to
        • Your bank name and account number

        Evidence Screenshots

        • All WhatsApp, Telegram, or SMS conversations with the scammer
        • Screenshots of any website, app, or link used in the scam
        • Screenshot of UPI payment confirmation from PhonePe, GPay, or your banking app
        • Any offer letter, job posting, or fake website shared by the scammer
        • Email communications if any

        Personal Documents

        • Your Aadhaar card, Voter ID, or any government ID (soft copy in .jpg or .png, under 5MB)
        • Your mobile number linked to the bank account

        Important: Do not delete any chats, messages, or screenshots. Even if you blocked the scammer — the evidence in those screenshots is what investigators will use. Store everything in a folder on your phone or email it to yourself before anything is accidentally deleted.

        Step 1 — Call 1930 Immediately (Do This First)

        Before filing any written complaint, call 1930 right now.

        This is India’s National Cybercrime Financial Fraud Helpline, available 24 hours a day, 7 days a week. It is completely free.

        Here is exactly what happens when you call:

        • The operator takes your details — transaction amount, UTR number, bank name, and the fraudster’s account details
        • Your complaint is instantly forwarded through a centralised system connected to all major banks and payment gateways
        • Authorities attempt to place a transaction hold or fund freeze request on the suspicious account
        • You receive an SMS with an acknowledgement number — save this, you will need it

        After the call, you must log in to cybercrime.gov.in within 24 hours to complete the formal written complaint using your acknowledgement number. The call alone is not sufficient — it must be followed up with the online complaint.

        What to Say When You Call 1930

        “I am a victim of cyber fraud. On [date] at [time], I was deceived into transferring ₹[amount] to UPI ID [UPI ID] / bank account [account number]. My bank is [bank name]. The UTR number of the transaction is [UTR number]. I request an immediate freeze on the beneficiary account.”

        Speak clearly and slowly. Give exact numbers. The operator will guide you through the rest.

        Step 2 — File Your Complaint on cybercrime.gov.in

        This is India’s official National Cyber Crime Reporting Portal, run by the Ministry of Home Affairs. Filing here creates a legal record of your complaint and triggers action by state cyber cells.

        How to File — Exact Steps

        1. Go to cybercrime.gov.in on your browser
        2. Click “File a Complaint”
        3. Click “Report Other Cyber Crime” for financial fraud, job scam, fake website, or investment fraud
        4. Fill in your personal details — name, state, district, PIN code
        5. In the complaint form, select the category — choose “Online Financial Fraud” for most scams
        6. Select the sub-category — UPI Fraud, Fake Job Scam, Investment Fraud, etc.
        7. Enter the incident date, time, and platform (WhatsApp, Telegram, website, etc.)
        8. In the description box — write a clear, factual account of what happened. Minimum 200 characters. Do not use special characters like #, $, @, ^
        9. Enter the bank name, account number, and UTR transaction number
        10. Upload your evidence screenshots and a copy of your ID
        11. Submit — you will receive a complaint reference number. Save this immediately. Your complaint is automatically routed to your State or UT cyber cell for action.

        Tips for Writing Your Complaint Description

        • Write in simple, factual language — what happened, when, how, how much
        • Include the exact scammer UPI ID or account number
        • Mention the platform — WhatsApp, Telegram, Instagram, job portal, etc.
        • Do not exaggerate or include unnecessary emotional content — stick to facts
        • A good description example: “On 18 March 2026, I received a WhatsApp message from +91-XXXXXXXXXX offering a part-time job for liking YouTube videos. After completing three tasks for which I was paid ₹450 via UPI, I was asked to deposit ₹5,000 to a ‘VIP task group’ UPI ID: fraud@ybl to earn ₹12,000. After payment, the contact disappeared. Total loss: ₹5,000. UTR: XXXXXXXXXX.”

        Step 3 — Contact Your Bank Immediately

        Parallel to calling 1930, call your bank’s fraud helpline. Do not wait for cybercrime.gov.in complaint first — do this at the same time.

        What to Say to Your Bank

        “I am a victim of a cyber fraud. On [date], I was deceived into transferring ₹[amount] to UPI ID [UPI ID] / account number [number]. I request you to immediately flag this transaction and send an emergency hold request to the beneficiary bank under RBI cybercrime guidelines. My 1930 acknowledgement number is [number] and my cybercrime.gov.in complaint reference is [number]. Please treat this as urgent.”

        Major Bank Fraud Helpline Numbers

        • SBI: 1800-111-109 or 1800-425-3800
        • HDFC Bank: 1800-202-6161
        • ICICI Bank: 1800-102-4242
        • Axis Bank: 1800-209-5577
        • Kotak Mahindra: 1860-266-0811
        • Bank of Baroda: 1800-102-4455
        • Punjab National Bank: 1800-180-2222
        • Paytm: 0120-4456-456
        • PhonePe: 080-68727374
        • Google Pay: 1800-419-0157

        Know your rights: Under RBI guidelines, if you report an unauthorised transaction within 3 working days and it was not due to your own negligence, your bank is required to refund the amount. Follow up in writing if your bank does not respond within 3 working days.

        Step 4 — Report the Scammer’s Phone Number on Sanchar Saathi

        Go to sancharsaathi.gov.in and click on “Chakshu” — this is the Government of India’s platform to report fraudulent phone numbers.

        Report the exact number used by the scammer. The Department of Telecommunications uses these reports to trace and block fraud numbers. Complaints made within 30 days are actively investigated. Reports after 30 days still help identify patterns and block serial offenders.

        This step takes under 5 minutes and helps protect thousands of other potential victims from the same number.

        Step 5 — File an FIR at Your Local Cyber Police Station

        An online complaint on cybercrime.gov.in is important — but for serious fraud, especially above ₹10,000, filing a physical FIR gives you a stronger legal position.

        When is an FIR Mandatory?

        • Loss above ₹10 lakh — under the new e-Zero FIR initiative, complaints involving losses above ₹10 lakh automatically generate a Zero FIR
        • When your bank asks for an FIR copy to process your refund
        • When you want to pursue legal action against the scammer
        • For identity theft, data breach, or harassment cases

        How to File an FIR

        1. Visit your nearest cyber police station or any police station
        2. Carry printed copies of all evidence — chats, payment receipts, screenshots, offer letters
        3. Carry your cybercrime.gov.in complaint reference number
        4. Request to file an FIR under Section 318(4) of BNS 2023 (cheating) and Section 66D of the IT Act (cheating using computer resources)
        5. Review the FIR carefully before signing — make sure all amounts and details are accurate
        6. Get a copy of the FIR with the FIR number and investigating officer’s name and contact

        What If Police Refuse to File an FIR?

        This still happens in some stations. If police refuse, remind them of Section 173 of BNSS 2023 (formerly Section 154 of CrPC), which legally mandates registering an FIR for cognizable offences. If they still refuse, file your complaint on cybercrime.gov.in — online complaints are monitored directly by the Ministry of Home Affairs and local police are mandated to act on them.

        Step 6 — Escalate If No Action Is Taken

        If you filed a complaint and received no response or action within a reasonable time, do not give up. You have escalation options.

        Escalate to RBI Banking Ombudsman

        If your bank refuses to acknowledge or act on your fraud complaint within 30 days, file a complaint against the bank at bankingombudsman.rbi.org.in. The RBI Ombudsman has authority to direct banks to process refunds in eligible fraud cases.

        Escalate to State Cyber Cell

        If local police are unresponsive, contact your state’s dedicated cyber crime cell directly. Most states now have a separate cyber crime division with dedicated officers for financial fraud cases.

        Escalate to National Consumer Helpline

        For e-commerce fraud, fake delivery scams, or online shopping fraud, file a complaint at consumerhelpline.gov.in or call 1800-11-4000.

        You can also use ScamDekho to verify any website link, UPI ID, or QR code before clicking or paying — completely free, no login required.

        Types of Cyber Scams You Can Report

        The cybercrime.gov.in portal accepts complaints for all of these:

        • UPI fraud and digital payment scams
        • Fake job offer and work-from-home scams
        • Online investment and trading scams
        • Fake loan app fraud
        • Digital arrest scam
        • Phishing — fake bank, UIDAI, or government websites
        • Online shopping fraud — fake products, no delivery
        • Fake donation and NGO scams
        • Identity theft and Aadhaar misuse
        • Social media hacking and impersonation
        • Sextortion and online blackmail
        • Fake customer care number fraud
        • SIM swap fraud
        • Ransomware and hacking

        Also Read: Fake Scheme Portals Are Defrauding Users-How to Spot Scams on Government Sites

        Quick Reference — All Important Links and Numbers

        • National Cybercrime Helpline: 1930 (24×7, free)
        • Online Complaint Portal: cybercrime.gov.in
        • Report Fraud Phone Numbers: sancharsaathi.gov.in (Chakshu)
        • RBI Banking Ombudsman: bankingombudsman.rbi.org.in
        • National Consumer Helpline: consumerhelpline.gov.in or 1800-11-4000
        • Check Suspicious Links and UPI IDs: scamdekho.in
        • PM CARES Fund (official): pmcares.gov.in
        • NGO Verification: ngodarpan.gov.in

        Key Takeaways

        • Call 1930 immediately after any cyber fraud — this is the most time-sensitive step
        • File a written complaint on cybercrime.gov.in within 24 hours of calling 1930
        • Contact your bank simultaneously — use the exact script provided above
        • Report the scammer’s number on Sanchar Saathi at sancharsaathi.gov.in
        • File a physical FIR for losses above ₹10,000 — especially if your bank needs it
        • Escalate to RBI Ombudsman if your bank does not respond within 30 days
        • Check any suspicious link or UPI ID on ScamDekho before clicking or paying
        • Never pay any fee to anyone who offers to help you recover your scammed money — that is a second scam

        Conclusion

        Getting scammed is not your fault. These are professional criminal networks that have spent years perfecting their techniques to deceive even the most careful people.

        But now you know exactly what to do. You have the helpline number. You have the portal link. You have the bank script. You have the escalation path.

        The most important thing is speed. Every hour you wait reduces your chance of recovery. So do not wait, do not feel ashamed, and do not think your case is too small to report. Even small amounts, when reported, help authorities track and shut down the networks behind these scams.

        And before your next online transaction — if you ever receive a suspicious link, a UPI ID from an unknown source, or a website that feels off — check it for free on ScamDekho before you click or pay. That one check could save you from needing this guide in the first place.

        Bookmark this page and share it with your family. The person who needs it most might not know this guide exists until it is too late.

        Report fast. Recover faster.